Compass Updates

Hand holding compass on Cypress Bank publication cover
The Compass Q3 2026

Bad Breadth: Beneath the Surface of Market Highs

Although the S&P 500 closed the third quarter with a strong year-to-date return of 11.8%, in our opinion, headline gains mask significant weakness underneath. Most constituent stocks lagged the broader index considerably in 2026 and our analysis found that:

Broad Declines: More than 70% of S&P 500 members sit at least 10% below their 52-week highs.

Steep Average Drawdowns: Across the S&P 500 index, the average and median pullbacks from 52-week highs are 20% and 17%, respectively.

Narrow Leadership: Only 6.5% of companies trade within 5% of their annual highs.

In our view, this narrow participation recently triggered an ominous historical precedent. Prior to September 21, 2026, the S&P 500 Index had rallied to within 1% of its all-time high level, while more constituent stocks reached 52-week lows than highs. Data indicates that this historical combination occurred only twice before: July 23, 1929, and December 21, 1999 (1).
Cartoon man exhales bad breath toward disgusted woman
While evidence suggests that these historical parallels often signal late-cycle vulnerability, we do not view an imminent crash on the scale of the 1930s or the dotcom unwind as an inevitability. Instead, we believe that an environment marked by thin breadth reinforces the critical importance of disciplined security selection, prudent position sizing, and robust portfolio construction.

At Cypress Bank & Trust, our investment process begins with a clear understanding of each client’s financial goals and risk tolerance. By seeking to build resilient, risk-managed portfolios, we aim to help our clients remain well-positioned to navigate periods of volatility and pursue their long-term financial objectives.
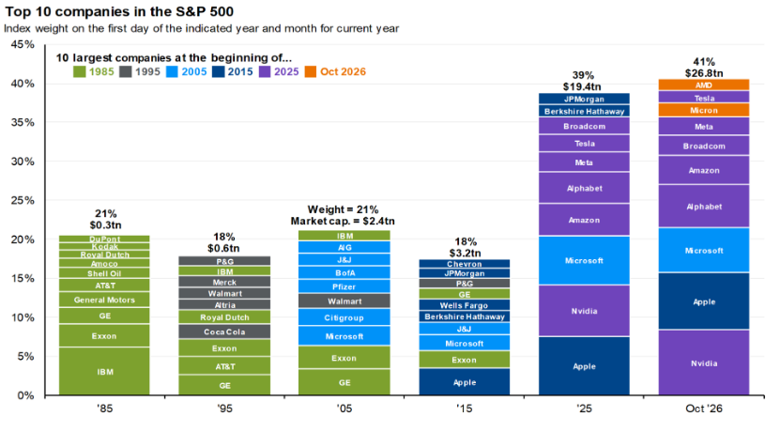
S&P 500 concentration among top ten companies rises sharply
Source: J.P. Morgan, FactSet, Standard & Poor’s. Data as of September 30, 2026.

Equity

The U.S. stock market continued to move higher in the third quarter, although at a slower pace than in the second quarter. The S&P 500 Index gained 2.03%, and the Nasdaq Composite rose nearly 2.5%, while the Dow Jones Industrial Average declined 2.7%. We presume that these results represented a moderation from the second quarter, when the S&P 500 Index rallied nearly 15% and finished the first half of 2026 with a gain of nearly 10% (2). The conflict with Iran appeared to remain a background consideration throughout the quarter. We assess that with the Strait of Hormuz still blocked and oil reaching above $100 per barrel during the quarter, energy prices and inflation remained important considerations for investors. Market performance data suggests that U.S. stocks outperformed many international markets during the quarter.

In our opinion, two forces drove the market this quarter: artificial intelligence and interest rates. AI-related stocks experienced a bumpy ride. We assess that the Philadelphia Semiconductor Index fell more than 11% for the quarter, pressured by profit-taking, concerns about competition from China, questions over how companies would fund their massive AI spending, and calls from prominent AI leaders to slow development (3). However, the largest names held firm. Microsoft rose 37.5%; Meta gained nearly 29%, and Nvidia added more than 14%, which helped keep the major indexes in positive territory (4).

We estimate that sector performance followed these themes. Energy led with a gain of about 16%, driven by higher oil & diesel prices rather than a broad economic upturn, and analysts expect energy earnings to roughly double from a year ago. Technology gained about 2.7%, but that strength was narrower than it appears given the weakness in semiconductors. Rate-sensitive areas struggled the most. Utilities fell about 13%, industrials nearly 11%, and consumer discretionary fell 7.2% (5).

We think that one of the more encouraging developments came from valuations. As the earnings of the underlying companies in the S&P 500 increased, its main valuation metric (price per earnings, P/E) fell from about 21.5 times at the beginning of June to roughly 19 times by the end of September, one of the sharpest declines in recent years, in other words the stock market became cheaper even as it moved higher (6).

Fixed Income & Economics

In our view, bonds had a difficult third quarter with The Federal Reserve serving as the main driver. At Jackson Hole in August, the Federal Reserve Chair Kevin Warsh made it clear that the summer softer inflation readings didn’t change his view, and markets quickly priced in a hike. The Fed followed through in their September meeting, raising rates by a quarter point to a range of 3.75%–4.00%. It was the Fed’s first increase since 2023, and its projections pointed to one more hike this year and no cuts in 2027. Short-term yields moved the most, with the 2-year Treasury rising about 71 basis points to 4.88%. Longer-term rates climbed as well. The 10-year Treasury yield rose from about 4.4% at the start of the third quarter to nearly 5.3% by the end of September, its highest level in about two decades As a result, mortgage rates are now around 7% (7).
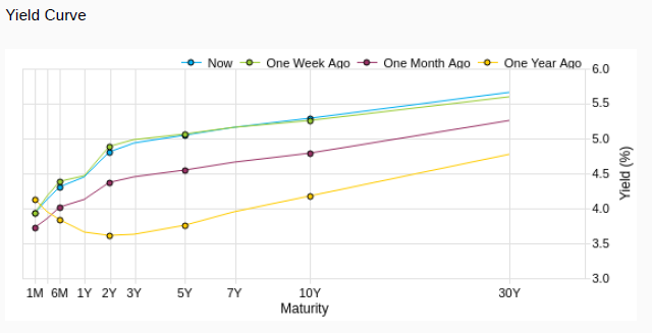
Yield curve chart comparing current and historical maturity rates
Source: FactSet. Data as of September 30th, 2026.

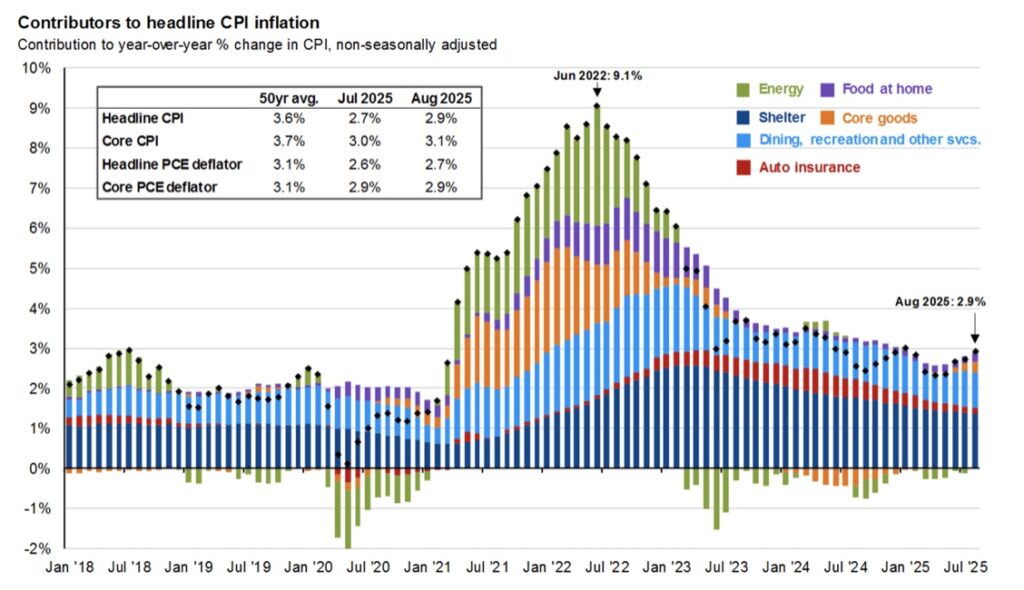
Evidence suggests that inflation remains the key issue. August CPI rose 3.4% from a year ago, driven largely by energy, with gasoline up more than 27% over the past year (8). The Fed’s preferred measure, PCE, offered some relief at quarter-end. Headline PCE eased to 3.4% and core PCE fell to 3.0%, both softer than expected. Still, core PCE has now been above the Fed’s 2% target for more than five years, which explains why the Fed remains cautious (9).

We have reason to believe that the labor market held up well in the third quarter. The unemployment rate held steady at 4.1% throughout the quarter. Layoffs remained low; job openings were stable, and hiring appears to be spreading across more industries. Wage growth was a weak spot. As pay increases continued to trail inflation, the purchasing power of workers slipped slightly (10). Overall, we estimate that the job market looks steady rather than strong, giving the Federal Reserve room to stay focused on inflation and supports the case for keeping interest rates higher for longer.
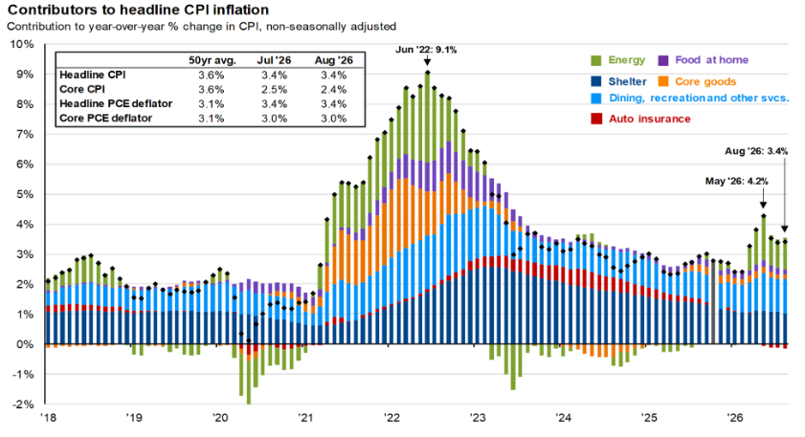
Stacked chart of contributors to U.S. headline CPI inflation
Source: J.P. Morgan, BLS, and FactSet. Data as of September 30, 2026.

Summary & Outlook

Despite the S&P 500 delivering a solid 11.8% return through the first nine months of 2026, we hold that the market’s strength has been far narrower than the headline numbers suggest (2). More than 70% of S&P 500 companies remain at least 10% below their 52-week highs, while the average stock is still down approximately 20% from its peak (1). The data indicates that only a small fraction of companies is trading near their highest levels of the year, highlighting a market increasingly driven by a handful of large-cap leaders. Historically,  research shows that such weak market breadth has often emerged late in market cycles, and the recent occurrence of the S&P 500 trading near record highs while more stocks reached new lows than new highs has only been observed twice before, in 1929 and 1999(1). In our opinion, while these comparisons warrant caution, they do not necessarily signal an imminent market downturn. Instead, we believe they reinforce the value of disciplined stock selection, diversification, and prudent risk management.

In our view, U.S. equities continued to advance during the third quarter, although gains moderated compared to the strong rally experienced earlier in the year. Data suggests that technology and artificial intelligence remained the dominant market themes, with companies such as Microsoft, Meta, and Nvidia posting significant gains that helped support major indexes despite weakness throughout much of the broader market. We have reason to believe that semiconductor stocks faced notable pressure amid concerns surrounding competition, funding requirements for AI investments, and regulatory scrutiny. Our research shows that energy was the quarter’s strongest-performing sector as elevated oil prices, driven by ongoing geopolitical tensions and disruptions in global supply chains, boosted earnings expectations. Meanwhile, evidence suggests that interest-rate-sensitive sectors including utilities, industrials, and consumer discretionary lagged. It is our position that stronger corporate earnings allowed market valuations to decline even as stock prices moved higher, leaving the S&P 500 trading at more reasonable earnings multiple by quarter end.

From our perspective, fixed income markets faced a challenging quarter as the Federal Reserve resumed tightening monetary policy, raising short-term interest rates and signaling that rates could remain elevated for an extended period. Treasury yields rose sharply across the curve, pushing 30-year fixed mortgage rates back above 7% and creating headwinds for bond investors. Inflation remains the Fed’s primary concern, though some measures showed modest improvement toward quarter-end (7). Our analysis found that the labor market continued to demonstrate resilience, with unemployment holding steady and layoffs remaining relatively low, providing support for economic growth despite tighter financial conditions. Looking ahead, we believe that the combination of persistent inflation, higher interest rates, and narrow market leadership underscores the importance of maintaining well-diversified portfolios that balance opportunity with risk. At Cypress Bank & Trust, we remain focused on building portfolios aligned with each client’s objectives, aiming to help our  clients remain well-positioned to navigate periods of volatility and pursue their long-term financial success.

As we enter the final months of 2026 and look ahead to 2027,  we think that investors face a market characterized by both opportunity and increasing complexity. We have reason to believe that economic growth remains positive; corporate earnings will continue to expand, and the labor market will  remain resilient despite higher borrowing costs. However, elevated interest rates, persistent inflation pressures, geopolitical tensions, and historically narrow market leadership suggest that volatility potentially remains a defining feature of the investment landscape. We consider that while a broader market correction cannot be ruled out, improving valuations and continued earnings growth potentially provides a constructive backdrop for long-term investors. We believe leadership is likely to broaden beyond a handful of mega-cap technology companies, creating opportunities in quality businesses that have lagged the market despite strong fundamentals.

For fixed income investors, we have reason to believe the sharp rise in yields during 2026 has significantly improved future return potential and restored bonds as an attractive source of income and diversification. We presume that if inflation continues to moderate, interest rates may begin to stabilize during 2027, providing support for both bond and equity markets. At Cypress Bank & Trust, we remain focused on building diversified, risk-managed portfolios tailored to each client’s objectives, based on our belief that a balanced approach to asset allocation, security selection, and risk management may help investors navigate changing market conditions and pursue potential opportunities over time.

With continued vigilance, we remain committed to helping you navigate both calm and turbulent markets as you pursue your long-term goals and objectives.

Sources:

(1) CNBC.com; TheStreet.com; Coinpaper.com.

(2) FactSet Research Systems.

(3) CNBC.com; FactSet Research Systems.

(4) WSJ.com; FactSet Research Systems.

(5) FactSet Research Systems.

(6) FactSet Research Systems.

(7) Federal Reserve Bank.

(8) U.S. Bureau of Labor Statistics

(9) U.S. Bureau of Economic Analysis

(10) U.S. Bureau of Labor Statistics

Disclaimer

Trust and Portfolio Management services offered by Cypress Bank & Trust are not insured by the FDIC; are not deposits, are not guaranteed; and are subject to investment risks, including possible loss. This does not constitute an offer or solicitation.

This information should not be considered investment advice. Opinions expressed reflect the judgment of the authors and are current opinions as of the date appearing in this material only. While every effort has been made to verify the information contained herein, we make no representations as to its accuracy and it should not be regarded as a complete analysis of the subjects discussed. Past performance does not predict future results. Content should not be construed as legal or tax advice. Always consult an attorney or tax professional regarding your specific legal or tax situation. All investing involves risk, including the loss of some or all of your investment.

Any indices and other financial benchmarks shown are provided for illustrative purposes only, are unmanaged, reflect reinvestment of income and dividends and do not reflect the impact of advisory fees. Investors cannot invest directly in an index. Comparisons to indexes have limitations because indexes have volatility and other material characteristics that may differ from a particular fund.

Certain information contained herein constitutes “forward-looking statements,” which can be identified by the use of forward-looking terminology such as “may,” “will,” “should,” “expect,” “anticipate,” “project,” “estimate,” “intend,” “continue,” or “believe,” or the negatives thereof or other variations thereon or comparable terminology. Due to various risks and uncertainties, actual events, results or actual performance may differ materially from those reflected or contemplated in such forward-looking statements. Nothing contained herein may be relied upon as a guarantee, promise, assurance or a representation as to the future.

Information obtained from third party sources is believed to be reliable but has not been independently verified and its accuracy or completeness cannot be guaranteed. No representation is made with respect to the accuracy, completeness, or timeliness of this document.

Specific investments described herein do not represent all investment decisions made by Cypress Bank & Trust. The reader should not assume that investment decisions identified and discussed were or will be profitable. Specific investment advice references provided herein are for illustrative purposes only and are not necessarily representative of investments that will be made in the future.
Hand holding compass beside July 2026 Compass publication title
The Compass Q2 2026

Happy 250th Birthday!

As America celebrates the anniversary of our Declaration of Independence, it is a timely reminder that while the American experiment remains marvelous, we still live in a world filled with geopolitical turmoil and challenges. Throughout the second quarter, the conflict in the Middle East continued to dominate the headlines, with shifting dynamics bringing new developments almost daily.

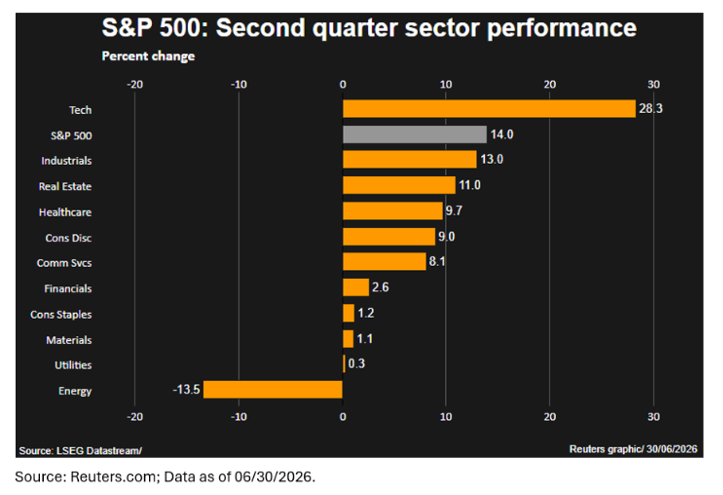
Typically, this type of global uncertainty triggers a negative reaction from the stock market. This quarter, however, we witnessed the exact opposite. The S&P 500 Index rose by 14.87% in the second quarter, marking its best quarterly return since Q2 of 2020 (1). Led primarily by semiconductor and chip stocks, with the PHLX Semiconductor Sector Index (SOX) surging 87.8%, the market largely brushed aside fluctuating oil prices and a more hawkish tone from the Federal Reserve regarding interest rates (2).

While it is easy to get caught up in the euphoria of a dramatic market rally or the latest investment fad, our approach remains steadfast. At Cypress Bank & Trust, your team seeks to construct your portfolio based on your specific goals and risk tolerance. This approach is intended to position your portfolio to pursue strong returns within a risk level you are comfortable taking.

Our investment process is rooted in sound fundamentals with the goal of helping clients navigate market turbulence. We believe our experience has taught us that chasing “hot” stocks or short-term trends rarely gives our clients the highest probability of achieving their long-term financial goals.

Equities

Equity markets continued to push higher during the quarter despite several headwinds, including elevated interest rates, ongoing geopolitical tensions, and concerns about whether corporate earnings can maintain their current pace of growth. The fact that stocks were able to advance in that environment highlights the market’s confidence in longer-term growth opportunities, particularly in areas such as artificial intelligence, automation, and other technologies that have the potential to improve productivity and drive future earnings.

Within the indices that describe the market the S&P 500 gained 14.9%, Dow Industrial Index gained 12.9%, and Nasdaq rose 21.4% (3). As we stand, the equity market continues to be heavily influenced by a relatively small group of large-cap technology and AI-related companies.

Outside of mega-cap technology, there are still opportunities, but they require a more selective approach. Valuation dispersion remains wide across sectors, market capitalizations, and geographies. Certain areas of the market still look expensive, while others have been largely ignored. This creates an opportunity for active management and thoughtful portfolio construction. Companies with strong balance sheets, durable cash flows, pricing power, and reasonable valuations should be better positioned if economic growth slows or if interest rates remain elevated.

S&P 500 second-quarter sector performance bar chart

Fixed Income

Longer-term Treasury yields moved higher during the second quarter as markets reassessed inflation, fiscal policy, and the future path of Federal Reserve policy. The peak of the 10-year Treasury yield during Q2 2026 was 4.69% with the 30-year yield hitting its highest level in 19 years at 5.2% (4).

The Federal Reserve remains in a difficult position. If it cuts rates too quickly, it risks reigniting inflation pressures. If it keeps policy restrictive for too long, it risks slowing the economy more than intended. For bond investors, this means the path of interest rates may remain choppy, especially as each inflation report and labor market release influences expectations for Fed policy.

Credit markets have also remained relatively resilient, but spreads are still tight in many areas. In our view, this is not the time to stretch too far for yield. High-quality bonds look attractive, but lower-quality credit requires more caution.

Overall, while recognizing that bond values may fluctuate, we continue to view fixed income as an important source of income and diversification.

U.S. Treasury yield curves for December 2025 and June 2026

Outlook

As we look toward the second half of 2026, we remain cautiously optimistic about financial markets despite an environment marked by geopolitical uncertainty, evolving trade relationships, and continued questions surrounding monetary policy. The resilience displayed by equity markets during the first half of the year suggests investors’ confidence in the underlying strength of the U.S. economy and corporate America. While market leadership has been concentrated in technology and artificial intelligence-related companies (5), we believe the next phase of the market may broaden beyond a handful of mega-cap stocks as earnings growth expands across additional sectors. Volatility should be expected, particularly as investors react to developments in the Middle East, fiscal policy debates, and ongoing economic data releases, but periods of uncertainty can create opportunities for disciplined long-term investors.

Within equities, valuations in certain segments of the market have become elevated following the strong rally, particularly among some AI and semiconductor-related companies. As a result, future returns may become more dependent on earnings growth rather than expanding valuation multiples. We believe a selective approach remains essential, favoring companies with strong balance sheets, sustainable competitive advantages, and consistent free cash flow generation. Opportunities continue to exist in areas of the market that have lagged the technology-driven advance, including select industrial, healthcare, financial, and dividend-oriented companies. Maintaining diversification across sectors, market capitalizations, and geographies remains an important component of risk management in an environment where market leadership could shift quickly.

In fixed income, higher interest rates have restored attractive income opportunities that have been absent for much of the past decade. While the Federal Reserve may continue to face challenges balancing inflation concerns with economic growth, current bond yields provide investors with meaningful income and potential portfolio stability. We continue to favor high-quality bonds and believe they may serve as an effective diversifier should economic growth moderate or market volatility increase. Overall, our investment outlook remains grounded in the belief that long-term success is achieved not by attempting to predict short-term market movements, but by maintaining a disciplined, diversified investment strategy aligned with each client’s unique goals, risk tolerance, and time horizon.

Always vigilant, our commitment to you is to navigate your portfolio through both calm and turbulent times to work towards your long-term goals and objectives.

References:

(1) FactSet Research Systems; data as of 06/30/2026.

(2) FactSet Research Systems; data as of 06/30/2026.

(3) FactSet Research Systems; data as of 06/30/2026.

(4) Cnbc.com, & CNN Business; data as of 06/30/2026.

(5) FactSet Research Systems; data as of 06/30/2026.

Disclosures

Trust and Portfolio Management services offered by Cypress Bank & Trust are not insured by the FDIC; are not deposits, are not guaranteed; and are subject to investment risks, including possible loss. This does not constitute an offer or solicitation.

This information should not be considered investment advice. Opinions expressed reflect the judgment of the authors and are current opinions as of the date appearing in this material only. While every effort has been made to verify the information contained herein, we make no representations as to its accuracy and it should not be regarded as a complete analysis of the subjects discussed. Past performance does not predict future results. Content should not be construed as legal or tax advice. Always consult an attorney or tax professional regarding your specific legal or tax situation. All investing involves risk, including the loss of some or all of your investment.

Any indices and other financial benchmarks shown are provided for illustrative purposes only, are unmanaged, reflect reinvestment of income and dividends and do not reflect the impact of advisory fees. Investors cannot invest directly in an index. Comparisons to indexes have limitations because indexes have volatility and other material characteristics that may differ from a particular fund.

Certain information contained herein constitutes “forward-looking statements,” which can be identified by the use of forward-looking terminology such as “may,” “will,” “should,” “expect,” “anticipate,” “project,” “estimate,” “intend,” “continue,” or “believe,” or the negatives thereof or other variations thereon or comparable terminology. Due to various risks and uncertainties, actual events, results or actual performance may differ materially from those reflected or contemplated in such forward-looking statements. Nothing contained herein may be relied upon as a guarantee, promise, assurance or a representation as to the future.

Information obtained from third party sources is believed to be reliable but has not been independently verified and its accuracy or completeness cannot be guaranteed. No representation is made with respect to the accuracy, completeness, or timeliness of this document.

Specific investments described herein do not represent all investment decisions made by Cypress Bank & Trust. The reader should not assume that investment decisions identified and discussed were or will be profitable. Specific investment advice references provided herein are for illustrative purposes only and are not necessarily representative of investments that will be made in the future.

Hand holding compass beside The Compass April 2026 title
The Compass Q1 2026

Too Hard

Famed investor Warren Buffett has a filtering mechanism when looking at investment opportunities. He separates opportunities into three boxes: “In,” “Out,” and “Too Hard”. When assessing complex, volatile, or misunderstood businesses, he famously places them in the “too hard” file, prioritizing his “circle of competence” over chasing difficult, risky, or uncertain investments. With the growing conflict in the Middle East others might guess on the geopolitical outcome, here at Cypress we focus on what is knowable rather than speculating. We have seen a dramatic rise in the price of oil which has at least temporarily reversed the weaker dollar trend, interest rate cut expectations and many of the equity themes that had been working last year and in the first two months of 2026.

Since the beginning of military action in February the markets have experienced wild fluctuations in asset prices that in many cases are reversed in short order. For the quarter the S&P 500 was down 4.63% as concerns about how much the economy would slow as a result of higher oil prices (1). Many sectors of the equity market performed even worse than the S&P 500, namely Financials, Consumer Discretionary and Technology were each down over 9% for the year (2).

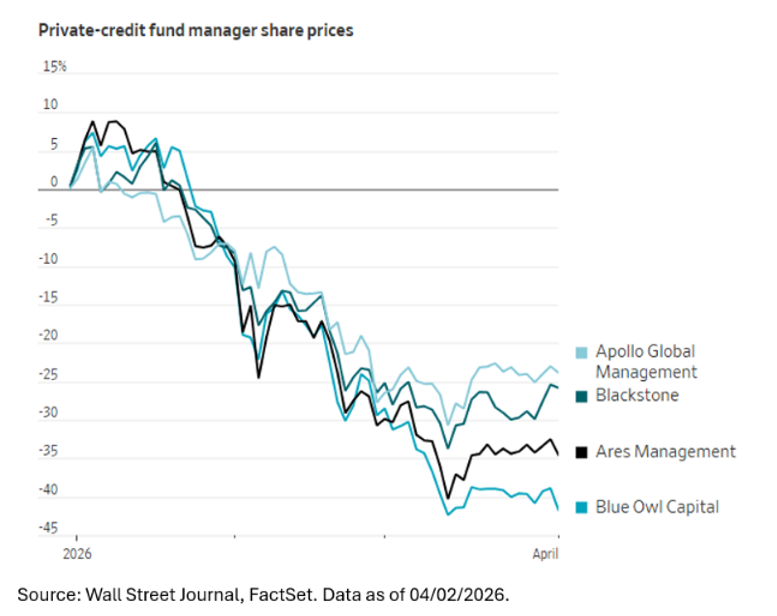
Although the headlines were consumed by the goings on across the globe there was one issue that received scant attention, that being the “liquidity mismatch” that many investors in the Private Investment sector are realizing. With each passing day it seems that yet another one of these funds has had to restrict their clients’ requests to access their investments. Fortunately for all our clients at Cypress Bank & Trust, we have not and will not invest our clients’ portfolios in investments that not only restrict liquidity and lack transparency, but many times create the need for delayed tax reporting. At Cypress, we always put our clients’ interests ahead of our own and do not create any proprietary investment vehicles that might compromise our fiduciary position with our clients.

Regarding the long-term impacts of the conflict in the Middle East, due to the number of variables that have yet to be defined it is difficult to discern a concrete thesis on how events will totally unfold. That being said it is entirely plausible that once the conflict is resolved we might experience higher levels of long-term interest rates and price of oil along with slower economic growth than was forecast before the conflict began. As always, your team at Cypress is diligently at the helm as we try to navigate these turbulent waters and attempt to mitigate the impacts of these uncertain events while keeping each of our clients’ bespoke circumstances as our North Star.

Private-credit fund manager share prices decline sharply in 2026
Equities

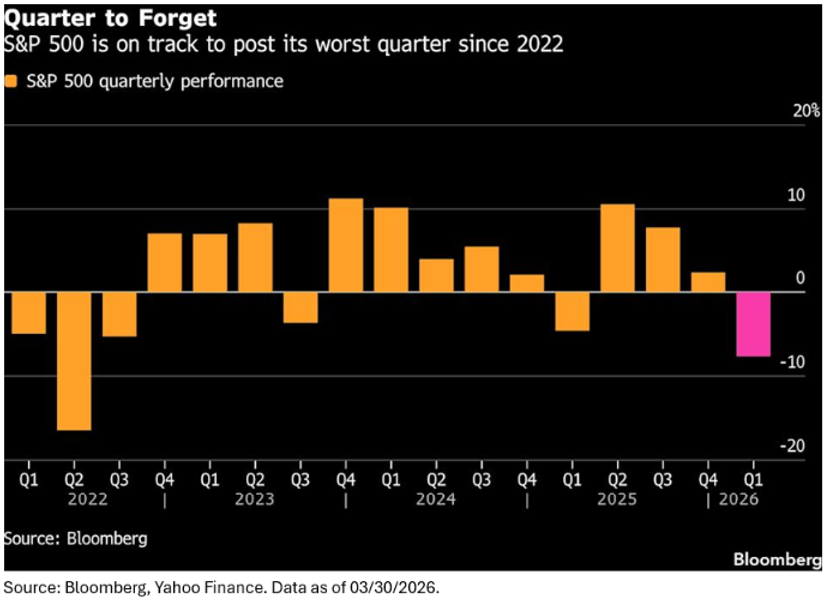
The U.S. equity market wrapped up a volatile first quarter of 2026 with its weakest performance since 2022, despite a sharp rebound on the final trading day. Markets came under pressure beginning in late February as escalating geopolitical tensions in the Middle East drove oil prices significantly higher, reviving inflation concerns and weighing on investor sentiment.

Performance across the major indexes reflected this volatility. The Nasdaq Composite was the most impacted, declining 7.1% for the quarter and briefly entering correction territory as higher yields weighed on technology and growth-oriented stocks. The S&P 500 finished the quarter down 4.6%, with late-March weakness erasing earlier gains despite still-solid underlying fundamentals. The Dow Jones Industrial Average held up relatively better, down 3.6% for the quarter, and rallied more than 1,100 points on the final day amid signs of diplomatic progress tied to the Iran conflict (3).

Bar chart of quarterly S&P 500 performance through Q1 2026

Beneath the surface, market leadership remained highly concentrated. Energy was the clear standout, up roughly 38% year-to-date as supply disruptions pushed oil prices above $100 per barrel (4). In contrast, large-cap technology and AI-related stocks pulled back meaningfully as investors reassessed valuations and the pace of expected returns on heavy capital spending. Financials were the weakest-performing sector, pressured by concerns around lending standards and private credit exposure.

From a broader economic standpoint, the Federal Reserve continued its “wait-and-see” approach as inflation remained sticky, leading markets to price in fewer rate cuts for 2026.

Consumer trends also remained uneven, with higher-income households continuing to spend, while lower-income consumers showed increasing strain, reflected in rising auto and credit card delinquencies.

Fixed Income

The bond market got off to a choppier start in 2026 as expectations for continued rate cuts gave way to a more cautious, “wait-and-see” approach from the Federal Reserve. After easing policy late last year, the Fed opted to pause in the first quarter as inflation proved more persistent and global tensions picked up.

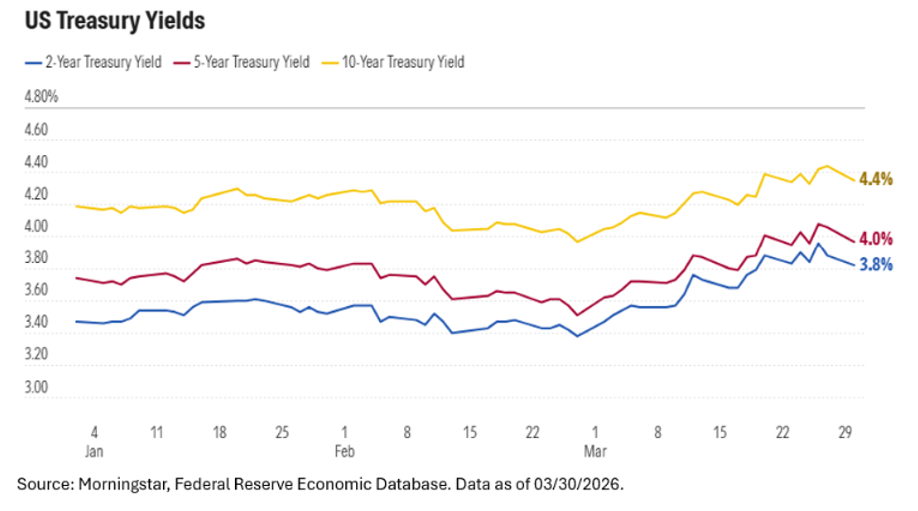
Treasury yields were especially volatile. Both short- and long-term rates rose as investors adjusted to the idea that additional rate cuts may take longer to materialize. The 10-year Treasury ended the quarter around 4.31%, while the 2-year yield climbed even more as optimism around near-term easing faded (5). The yield curve continues to gradually steepen, and the intermediate segment of the curve has been an area of focus for investors looking to balance income and risk.

Line chart showing rising US Treasury yields in March 2026.
Several factors are contributing to the steepening of the yield curve. The Federal Reserve held rates steady at its January and March meetings, emphasizing patience as inflation remains elevated. At the same time, geopolitical developments, particularly involving Iran, pushed oil prices above $100 per barrel, reintroducing inflation concerns and prompting markets to largely price out rate cuts for the rest of 2026. On top of that, rising federal debt levels and increased defense spending have placed added pressure on longer-term yields.

Looking ahead, fixed income continues to play an important role in portfolios, especially in periods of uncertainty and market volatility. We remain focused on thoughtful positioning across the bond market, aiming to generate consistent income while managing interest-rate risk as the economic and policy backdrop continues to evolve.

Outlook

The first quarter of 2026 proved to be a turbulent and challenging period for global financial markets. U.S. equities faced a difficult three-month stretch, driven by a combination of escalating tariff anxieties, renewed skepticism around AI valuations, and mounting concerns in private credit markets — resulting in the S&P 500 closing the quarter down roughly 4%, its weakest quarterly performance since Q3 2022 (6). Technology stocks were hit particularly hard, with U.S. software stocks declining sharply through late February as investors grew concerned that new AI capabilities could threaten the software-as-a-service model and questioned whether hyperscaler’s could justify ever-increasing AI capital expenditures. Meanwhile, a major outbreak of conflict in the Middle East rattled global sentiment, driving Brent oil prices up by 63% in March alone — the largest single-month surge in four decades — and effectively disrupting the critical Strait of Hormuz.

Against this backdrop, commodities emerged as the standout asset class. The Bloomberg Commodity Index was the top performer of the quarter, rising over 24%, as energy and grain prices surged in response to the geopolitical shock. The energy sector led all S&P 500 sectors, gaining 38% in Q1 and standing as the only sector to post positive returns in March (7). Fixed income offered little shelter, as government bond markets sold off sharply across the globe, with hopes for central bank rate cuts giving way to fears of stagflation — prompting markets to shift from pricing in cuts at the Fed and ECB to pricing in potential rate hikes.

Credit spreads widened in both high yield and investment grade markets, while a stronger U.S. dollar and elevated geopolitical risk weighed on emerging market debt. The remainder of 2026 is shaping up to be a market environment defined by cautious optimism, with several key forces in play. Goldman Sachs expects sturdy global growth of around 2.8%, with the U.S. likely to outperform on the back of reduced tariff drag, tax cuts, and easier financial conditions — though that optimism comes with caveats (8). Markets have already priced in a lot of anticipated good news, including Fed rate cuts, stimulus from fiscal legislation, and the belief that AI adoption will dramatically boost corporate profitability, leaving limited room for additional upside surprises. On the rates front, Morgan Stanley expects government bond yields to stay range-bound in a tale of two halves — a front-loaded rally as the Fed cuts rates pushing 10-year yields lower by mid-year, before drifting higher into Q4, with the dollar following a similar arc (9). AI remains the dominant market theme, spreading beyond tech into banking, healthcare, logistics, and utilities, and anchoring the bullish case for U.S. equities — though elevated valuations mean any signs of AI skepticism could trigger episodes of volatility. Wells Fargo cautions that tariff impacts may slow the economy and nudge inflation higher in the near term, before positive policy and technology spending trends reverse those conditions toward year-end, with yield and credit quality remaining the key metrics to watch. Overall, the consensus leans constructive but acknowledges a narrow margin for error — investors who stay diversified and agile are best positioned to navigate what promises to be a nuanced second half of the year.

Always vigilant, our commitment to you is to navigate your portfolio through both calm and turbulent times to work towards your long-term goals and objectives.

References:

(1) FactSet; data as of 03/31/2026.

(2) FactSet, Fidelity Sector Performance; data as of 03/31/2026.

(3) FactSet; data as of 03/31/2026.

(4) Cnbc.com, Fidelity Sector Performance; data as of 03/31/2026.

(5) Cnbc.com, FactSet; data as of 03/31/2026.

(6) FactSet, data as of 03/31/2026.

(7) FactSet, Fidelity Sector Performance; data as of 03/31/2026.

(8) Goldman Sachs; data as of December of 2025.

(9) CME Group FedWatch, data as of 03/31/2026.

Disclosures

Trust and Portfolio Management services offered by Cypress Bank & Trust are not insured by the FDIC; are not deposits, are not guaranteed; and are subject to investment risks, including possible loss. This does not constitute an offer or solicitation.

This information should not be considered investment advice. Opinions expressed reflect the judgment of the authors and are current opinions as of the date appearing in this material only. While every effort has been made to verify the information contained herein, we make no representations as to its accuracy and it should not be regarded as a complete analysis of the subjects discussed. Past performance does not predict future results. Content should not be construed as legal or tax advice. Always consult an attorney or tax professional regarding your specific legal or tax situation. All investing involves risk, including the loss of some or all of your investment.

Any indices and other financial benchmarks shown are provided for illustrative purposes only, are unmanaged, reflect reinvestment of income and dividends and do not reflect the impact of advisory fees. Investors cannot invest directly in an index. Comparisons to indexes have limitations because indexes have volatility and other material characteristics that may differ from a particular fund.

Certain information contained herein constitutes “forward-looking statements,” which can be identified by the use of forward-looking terminology such as “may,” “will,” “should,” “expect,” “anticipate,” “project,” “estimate,” “intend,” “continue,” or “believe,” or the negatives thereof or other variations thereon or comparable terminology. Due to various risks and uncertainties, actual events, results or actual performance may differ materially from those reflected or contemplated in such forward-looking statements.

Nothing contained herein may be relied upon as a guarantee, promise, assurance or a representation as to the future.

Information obtained from third party sources is believed to be reliable but has not been independently verified and its accuracy or completeness cannot be guaranteed. No representation is made with respect to the accuracy, completeness, or timeliness of this document.

Specific investments described herein do not represent all investment decisions made by Cypress Bank & Trust. The reader should not assume that investment decisions identified and discussed were or will be profitable. Specific investment advice references provided herein are for illustrative purposes only and are not necessarily representative of investments that will be made in the future.

Hand holding compass, Cypress Bank magazine cover
The Compass Q3 2025

Time to Hunker Down

One of the many lessons learned from living in Florida is that every year brings with it Hurricane Season. At the start of each season, weather experts run their models, weighing countless variables and historical patterns, to forecast how many storms may develop and how many might become hurricanes. Some years, the storms fizzle and we are spared the worst. Other years, their models prove prescient, and people in the path of nature’s wrath face devastating consequences.
The stock market often presents a similar dynamic. At the risk of sounding like “Chicken Little,” we see a set of conditions today that give us pause. These factors do not guarantee a storm is coming, but they do warrant greater vigilance. Specifically, three stand out:

i. Valuation

The S&P 500 is trading at a Cyclically Adjusted Price-to-Earnings (CAPE) ratio above 38 for three consecutive months. In the past century, this has only happened twice — in 1999 and late 2021. Historically, this ratio ranges between 15 and 22(1).

ii. Market Concentration

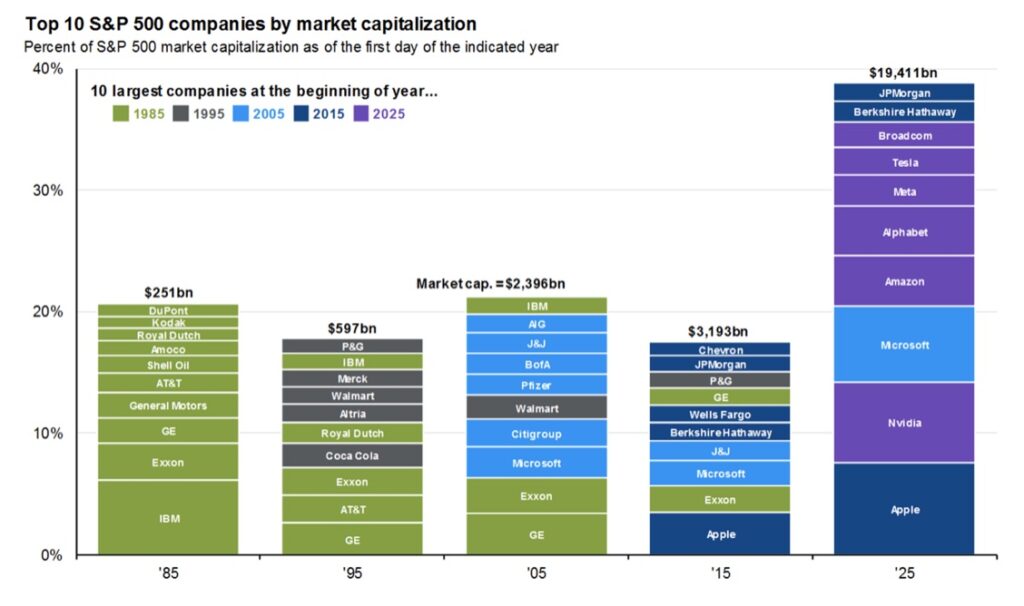
The top ten stocks now account for nearly 38% of the S&P 500, compared with a historical range of 20–25%. Earnings growth has also narrowed, with Information Technology and Communication Services responsible for 70% of S&P earnings growth since late 2022 and 90% over the past year (2).

iii. Leverage

Margin debt — credit extended against marketable securities — has surpassed $1 trillion. It has grown 33% in the past year, nearly twice the pace of the S&P 500 itself (3).

Like hurricane forecasts, these signals do not tell us precisely when or if a market storm will arrive. What they do suggest is that the conditions are in place. At Cypress Bank & Trust, our role is to prepare clients to withstand whatever comes.

Our investment philosophy is never to be “all in” or “all out.” Instead, we manage portfolios that balance risk and reward in the context of each client’s individual circumstances, income needs, and long-term goals. By budgeting for risk and structuring portfolios with resilience, we help clients weather the inevitable storms and continue on the path toward their objectives.

Top 10 S&P 500 companies by market capitalization over time.
Figure 1: JPMorgan Asset Management, Bloomberg, S&P.  Guide to the Markets – 09/30/2025

Equity Market

The U.S. equity market delivered robust gains in the third quarter, with all major indexes including the S&P 500, Nasdaq Composite, and Dow Jones Industrial Average reaching new record highs. This rally was fueled by several key factors: stronger-than-expected Q2 earnings, sustained momentum in artificial intelligence (AI) across semiconductors and the broader tech sector, growing expectations of Federal Reserve rate cuts later in the year, and a swift rebound from the tariff-driven selloff in April (4).

Technology led the third quarter sector performance with a 14% return, followed by Communications, which gained 12%. The continued acceleration of AI innovation and investment was a major catalyst, with mega-cap tech firms like Apple, Alphabet, and Nvidia driving much of the upside (5).

On the currency front, the U.S. Dollar Index (DXY) declined 9.5% year-to-date, reflecting broad weakness against major global currencies. This depreciation supported gains in hard assets, particularly precious metals. Silver stood out with a 28% surge, benefiting from both safe-haven demand and strong industrial usage. Gold also posted a solid 16% quarterly gain, climbing to a record high above $3,800 per ounce, as investors sought protection amid geopolitical tensions and concerns over elevated equity valuations (6).

Fixed Income

In a widely anticipated move, the Federal Reserve lowered its benchmark interest rate in September for the first time in a year, adjusting the target range to 4.00%–4.25%. This shift toward a more accommodative stance was driven by growing signs of labor market weakness, although inflation measures are proving sticky above the Federal Reserve 2% target. The rate cut provided a clear boost to fixed income markets, reinforcing expectations that the Fed will continue easing at a measured pace into 2026. Current projections by analysts and investors suggest the policy rate could settle between 3.0% and 3.5%, as officials weigh persistent inflation pressures against a softening employment backdrop (7).

Graph showing contributors to headline CPI inflation, 2018-2025.
Figure 2: JPMorgan Asset Management, Bloomberg, S&P.  Guide to the Markets – 09/30/2025

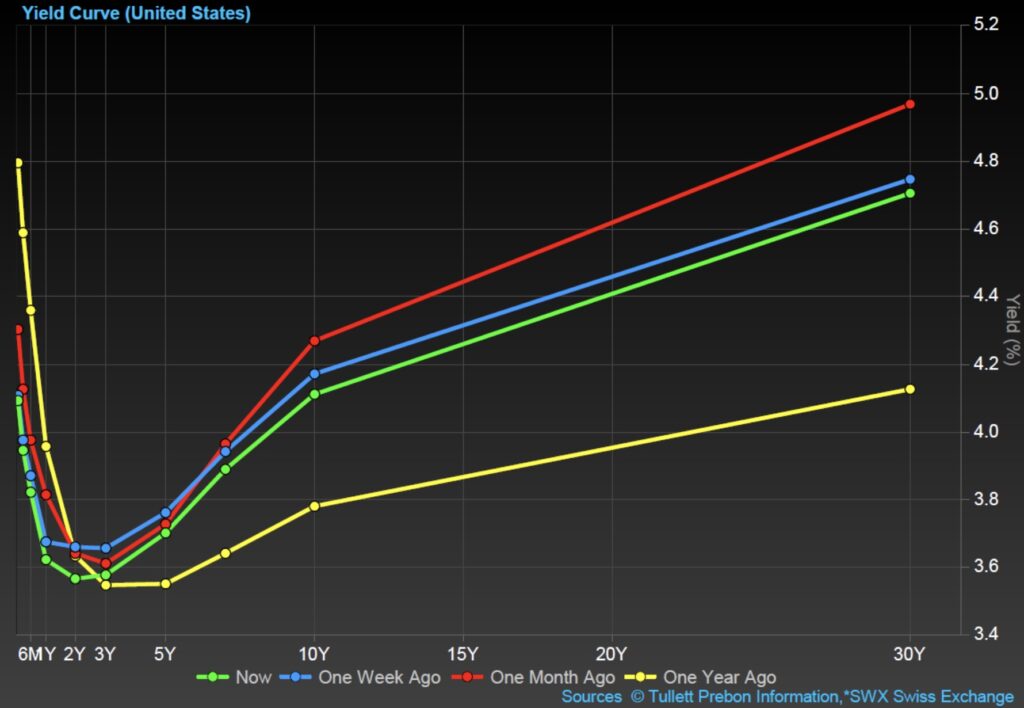
Treasury yields declined across the curve during Q3, contributing to a steepening yield curve. The 10-year Treasury yield ended the quarter near 4.10%, while the 2-year yield fell to 3.54%, reflecting expectations of further rate cuts. Meanwhile, the 30-year yield remained elevated for most of the third quarter, hovering around 5% before closing at 4.7%, driven by concerns over long-term fiscal sustainability and policy uncertainty (8).

US yield curve comparison chart
Figure 3:  FactSet Dashboard, Tuller Prebon Information, 10/01/2025.

Outlook: Q4 2025 and Beyond

As we enter the final quarter of 2025, financial markets are showing signs of cautious optimism. U.S. equities continue to perform well, particularly in the technology sector, driven by strong earnings and sustained investment in AI infrastructure. While inflation has moderated, global trade tensions and sector-specific headwinds—especially in manufacturing and diagnostics—are contributing to volatility. Ongoing monitoring of interest rate trends and geopolitical developments should dominate the headlines in the short term and be key drivers of the market’s direction.

Looking ahead to 2026, the outlook remains constructive. Analysts anticipate continued strength in U.S. equities, supported by easing monetary policy and robust consumer demand. The Federal Reserve is expected to maintain its rate-cutting trajectory, which could stimulate investment and support valuations across sectors. With the major markets near or at all-time highs, support from monetary and/or fiscal policy may not only be needed, but it may also already be priced in. However, risks such as persistent services inflation, wage pressures, and global policy uncertainty—particularly around U.S.-China trade relations—may impact margins and investor sentiment.

While short-term market fluctuations and macroeconomic uncertainties—such as inflation persistence and global trade tensions — may create volatility, we encourage clients to stay focused on their long-term financial goals. Diversification remains a key strategy for managing risk and smoothing returns across changing market conditions. By maintaining a disciplined approach and resisting the urge to react to short-term noise, investors can better position themselves to benefit from long-term growth opportunities. Our team is here to help you evaluate your portfolio, ensure alignment with your objectives, and make thoughtful adjustments as needed to navigate the road ahead with confidence.

Always vigilant, our commitment to you is to navigate your portfolio through both calm and turbulent times to meet your long-term goals and objectives.

Sources:

(1) Gurufocus.com; Ycharts.com. S&P 500 Shiller CAPE Ratio
(2) FactSet Earnings Insight 10/03/2025; FactSet Dashboard
(3) First Trust, Three on Thursday, 07/31/2025
(4) Yahoo.com, Dow, S&P 500, Nasdaq notch records on AI buzz even as government shutdown drags on, 10/02/2025
(5) Fidelity.com, Sector Returns, 10/01/2025
(6) FactSet Dashboard, 10/01/2025
(7) CME Group, CME FedWatch Tool, 10/01/2025
(8) CNBC.com, https://www.cnbc.com/bonds/


Disclosures

Trust and Portfolio Management services offered by Cypress Bank & Trust are not insured by the FDIC; are not deposits, are not guaranteed; and are subject to investment risks, including possible loss. This does not constitute an offer or solicitation. 

This information should not be considered investment advice. Opinions expressed reflect the judgment of the authors and are current opinions as of the date appearing in this material only. While every effort has been made to verify the information contained herein, we make no representations as to its accuracy and it should not be regarded as a complete analysis of the subjects discussed. Past performance does not predict future results. Content should not be construed as legal or tax advice. Always consult an attorney or tax professional regarding your specific legal or tax situation. All investing involves risk, including the loss of some or all of your investment. 

Any indices and other financial benchmarks shown are provided for illustrative purposes only, are unmanaged, reflect reinvestment of income and dividends and do not reflect the impact of advisory fees. Investors cannot invest directly in an index. Comparisons to indexes have limitations because indexes have volatility and other material characteristics that may differ from a particular fund. 

Certain information contained herein constitutes “forward-looking statements,” which can be identified by the use of forward-looking terminology such as “may,” “will,” “should,” “expect,” “anticipate,” “project,” “estimate,” “intend,” “continue,” or “believe,” or the negatives thereof or other variations thereon or comparable terminology. Due to various risks and uncertainties, actual events, results or actual performance may differ materially from those reflected or contemplated in such forward-looking statements. Nothing contained herein may be relied upon as a guarantee, promise, assurance or a representation as to the future. 

Information obtained from third party sources is believed to be reliable but has not been independently verified and its accuracy or completeness cannot be guaranteed. No representation is made with respect to the accuracy, completeness, or timeliness of this document. 

Specific investments described herein do not represent all investment decisions made by Cypress Bank & Trust. The reader should not assume that investment decisions identified and discussed were or will be profitable. Specific investment advice references provided herein are for illustrative purposes only and are not necessarily representative of investments that will be made in the future. 

Compass in hand, Cypress Bank quarterly publication
The Compass Q2 2025

“Investing is easier than you think, but harder than it looks.”
– Warren Buffett

At this year’s Berkshire Hathaway annual meeting, Warren Buffett announced that he will retire at the end of 2025—marking the close of what is likely the most extraordinary investing career any of us will witness. Over the years, Buffett has shared countless insights and principles, but few are as timeless as the one above.

In this quote, Buffett reminds us that the foundations of sound investing—diversification, patience, and long-term thinking—are not complicated. Yet, what makes investing difficult is managing our own behavior. Emotions like fear, greed, and impatience can quickly derail even the most straightforward strategy.

An important corollary to this idea is Amara’s Law, which states: “We tend to overestimate the effect of a technology in the short run and underestimate the effect in the long run.” We’ve seen this play out time and again—whether with electric vehicles, the internet, or artificial intelligence. Innovations often go through a predictable cycle: the initial burst of enthusiasm, followed by a period of disillusionment, and eventually, a more measured and transformative impact.

For investors, the challenge is recognizing where we are in this cycle—without the benefit of hindsight.

At Cypress Bank & Trust, we aim to address this challenge by constructing and managing client portfolios using time-tested principles. Our disciplined approach emphasizes diversification, patience, and a deep understanding of each client’s goals and circumstances. We don’t chase trends or react to headlines. Instead, we strive to deliver lasting value through thoughtful, long-term strategies.

By staying committed to these principles, we seek to help our clients navigate market turbulence with confidence—always with an eye toward the future they have told us what matters most.

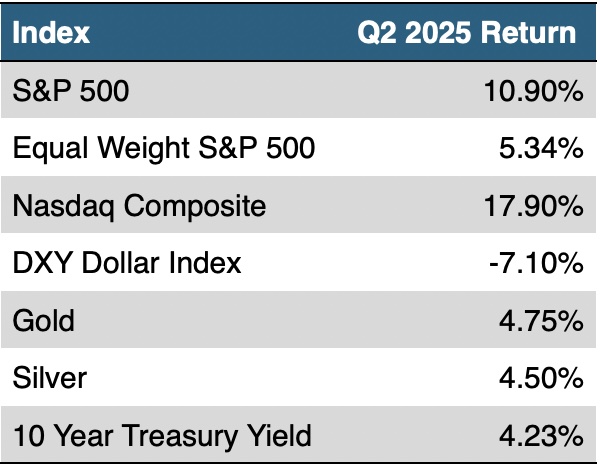
Q2 2025 index returns: S&P 500, Nasdaq, Gold.
Source: FactSet. Data as of 06/30/2025.

Equities

The second quarter of 2025 was marked by heightened volatility in the equity markets, not seen since the second half of 2022. It tested investor conviction but also served to make way for good long-term opportunities. Fueled by the uncertainties imposed by the Tariffs, the S&P 500 hit correction territory and closed at its lowest level this year on April 8th, down 18.9% from its all-time high. By the end of June, the index clawed its way back and reached a new all-time high [1], driven by a potential ceasefire between Israel and Iran, and a looming trade deal with China and other nations. Despite a steep drawdown in early April, the Technology sector finished the second quarter as the best performing sector, returning 23.54%[2]. The Magnificent 7 stocks have returned 18.6% through the second quarter of 2025 outpacing the other 493 companies in the S&P 500 index by nearly 14 percentage points[3].

The Federal Reserve held rates steady in their two meetings this quarter, signaling that interest rate cuts may occur in 2025 if inflation eases and the labor market softens. As much as we have seen the Consumer Price Index easing since the beginning of the year from 3% in January to as low as 2.3% in April’s reading, in the most recent release from the Personal Consumption Expenditure it indicated that inflation has started to creep up as of June[4].

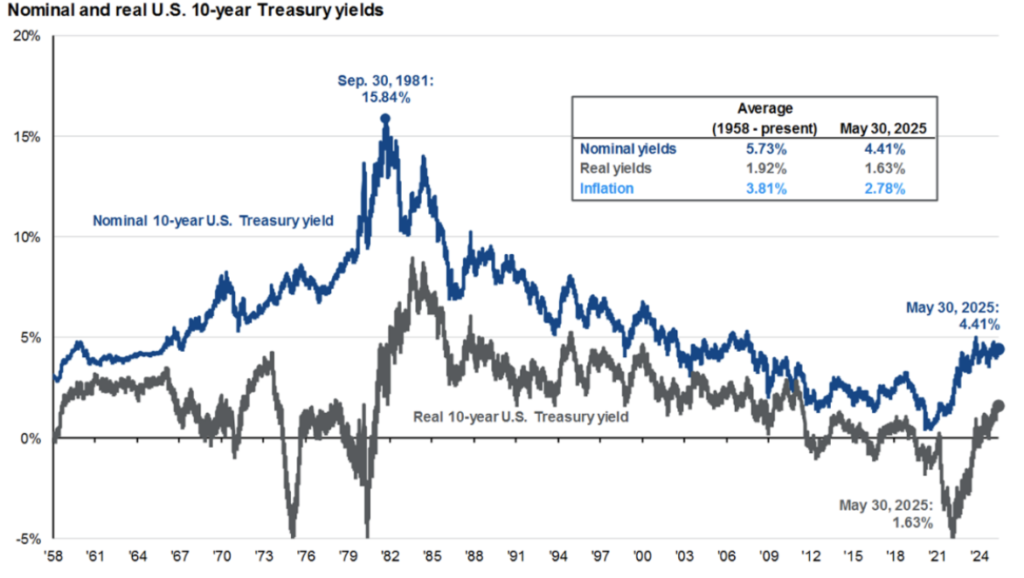
Graph of U.S. 10-year Treasury yields, 1958-2025.
Source: BLS, FactSet, Federal Reserve, J.P. Morgan Asset Management. Data as of 05/30/2025.

Fixed Income

The second quarter saw a high degree of yield swings in the U.S. fixed income markets, as investors had to navigate a terrain marked by rising yields, fiscal concerns, and shifting forecasts around the Federal Reserve’s interest rate policy. Longer maturity U.S. Treasuries sold off, pushing the twenty- and thirty-year yields above 5.1%, levels not seen in years, amid growing concerns over ballooning federal debt and the fiscal budget. As a consequence, long-term Treasuries returned -2.82% during the second quarter as measured by the iShares Twenty-Year Treasury ETF, ticker TLT [5].

US yield curve comparison over two years

Source: FactSet, Tullet Prebon Information. Data as of 06/30/2025.

While the Federal Reserve held rates steady in the second quarter, signaling a cautious path forward, investors began expecting interest rate cuts by September, contingent on how inflation and labor market data evolves until then. This resulted in a bond market that felt like anything but a safe haven with higher-than-normal volatility. 

Outlook

As we enter the second half of 2025, the financial markets continue to navigate a landscape shaped by cooling inflation, stable economic growth, and the Federal Reserve’s anticipated policy shift. With inflation steadily trending lower, the Fed is widely expected to implement one or two interest rate cuts before year-end. This easing cycle, coupled with resilient consumer and business activity, provides a constructive backdrop for both stock and bond markets—though geopolitical risks and the execution and implementation of tariff policy will add near-term volatility.

Equity markets have been largely supported by strong earnings and investor optimism, particularly in the technology sector. Looking ahead, we expect market leadership to broaden. Companies with healthy balance sheets, strong cash flow, and the ability to adapt to shifting conditions will continue to stand out.

In the fixed income space, higher yields are offering more compelling opportunities than we’ve seen in recent years. Investors are finding value across high-quality bonds, including Treasuries, municipals, and investment-grade corporates. Overall, staying diversified, maintaining a long-term perspective, and focusing on quality will be key strategies for navigating the months ahead.

Always vigilant, our commitment to you is to navigate your portfolio through both calm and turbulent times to work towards your long-term goals and objectives.

Footnote 1: Reuters.com, S&P 500, Nasdaq close at record highs. Published on 06/30/2025.
Footnote 2: Fidelity Sector Returns, data as of 07/01/2025.
Footnote 3: J.P. Morgan Asset Management, Review of markets over Q2 of 2025.
Footnote 4: U.S. Bureau of Labor Statistics, data as of 06/30/2025.
Footnote 5: FactSet Research Systems, data as of 07/01/2025.

Disclosures

Trust and Portfolio Management services offered by Cypress Bank & Trust are not insured by the FDIC; are not deposits, are not guaranteed; and are subject to investment risks, including possible loss. This does not constitute an offer or solicitation.

This information should not be considered investment advice. Opinions expressed reflect the judgment of the authors and are current opinions as of the date appearing in this material only. While every effort has been made to verify the information contained herein, we make no representations as to its accuracy and it should not be regarded as a complete analysis of the subjects discussed. Past performance does not predict future results. Content should not be construed as legal or tax advice. Always consult an attorney or tax professional regarding your specific legal or tax situation. All investing involves risk, including the loss of some or all of your investment.

Any indices and other financial benchmarks shown are provided for illustrative purposes only, are unmanaged, reflect reinvestment of income and dividends and do not reflect the impact of advisory fees. Investors cannot invest directly in an index. Comparisons to indexes have limitations because indexes have volatility and other material characteristics that may differ from a particular fund. 

Certain information contained herein constitutes “forward-looking statements,” which can be identified by the use of forward-looking terminology such as “may,” “will,” “should,” “expect,” “anticipate,” “project,” “estimate,” “intend,” “continue,” or “believe,” or the negatives thereof or other variations thereon or comparable terminology. Due to various risks and uncertainties, actual events, results or actual performance may differ materially from those reflected or contemplated in such forward-looking statements. Nothing contained herein may be relied upon as a guarantee, promise, assurance or a representation as to the future. 

Information obtained from third party sources is believed to be reliable but has not been independently verified and its accuracy or completeness cannot be guaranteed. No representation is made with respect to the accuracy, completeness, or timeliness of this document. 

Specific investments described herein do not represent all investment decisions made by Cypress Bank & Trust. The reader should not assume that investment decisions identified and discussed were or will be profitable. Specific investment advice references provided herein are for illustrative purposes only and are not necessarily representative of investments that will be made in the future. 

Compass in hand, Cypress Bank publication April 2025.
The Compass Q1 2025

“How puzzling all these changes are! I’m never sure what I’m going to be, from one minute to another.”
Alice from Alice in Wonderland by Lewis Carroll


So far 2025 seems to be a page taken out of Lewis Carroll’s classic Alice in Wonderland. Although we haven’t yet seen the Red Queen or the Mad Hatter the way the year is shaping up, we cannot entirely rule out those possibilities. We have seen a market correction, as defined by a decline in the stock market index from peak to trough of at least 10%, full blown rallies in stock prices that have seen the markets add near 3% to their value in a matter of days, and a constant flow of announcements coming out that drive investor sentiment swinging wildly between despair and euphoria.

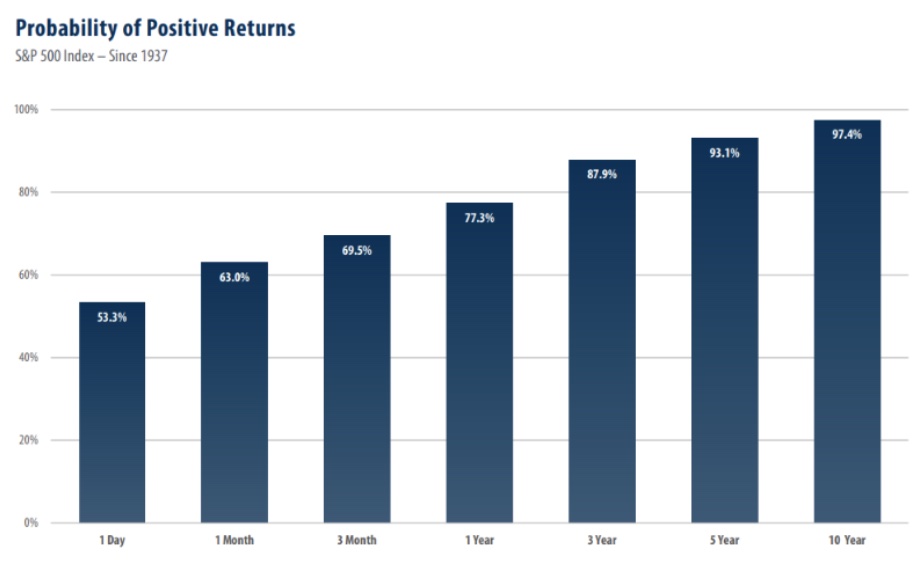
Despite the volatility, our approach at Cypress has remained grounded in a steady, long-term view. We continue to focus on diversification and strategic asset allocation to potentially minimize risk while seizing potential opportunities in the market. While the S&P 500 in the first quarter of 2025 ended down 4.59%[1], other segments of the market demonstrated resilience in the face of turbulence and turned positive returns. It is a reminder that while the markets may be unpredictable in the short term, patience and disciplined investment strategies may still yield positive results over time.

As we navigate through these unpredictable times, we want to reassure you that we are closely monitoring the developments in the financial markets, adjusting portfolios where necessary, and continuing to work on your behalf to secure your long-term financial goals. We understand that the market’s emotional rollercoaster can create anxiety, but we are here to help you stay the course, making decisions that aim to align with your objectives, not the day-to-day fluctuations.

S&P 500 positive return probabilities by duration.
Figure 1: Source – First Trust, Bloomberg. Data from 12/31/1996 – 12/31/2024.

Equities

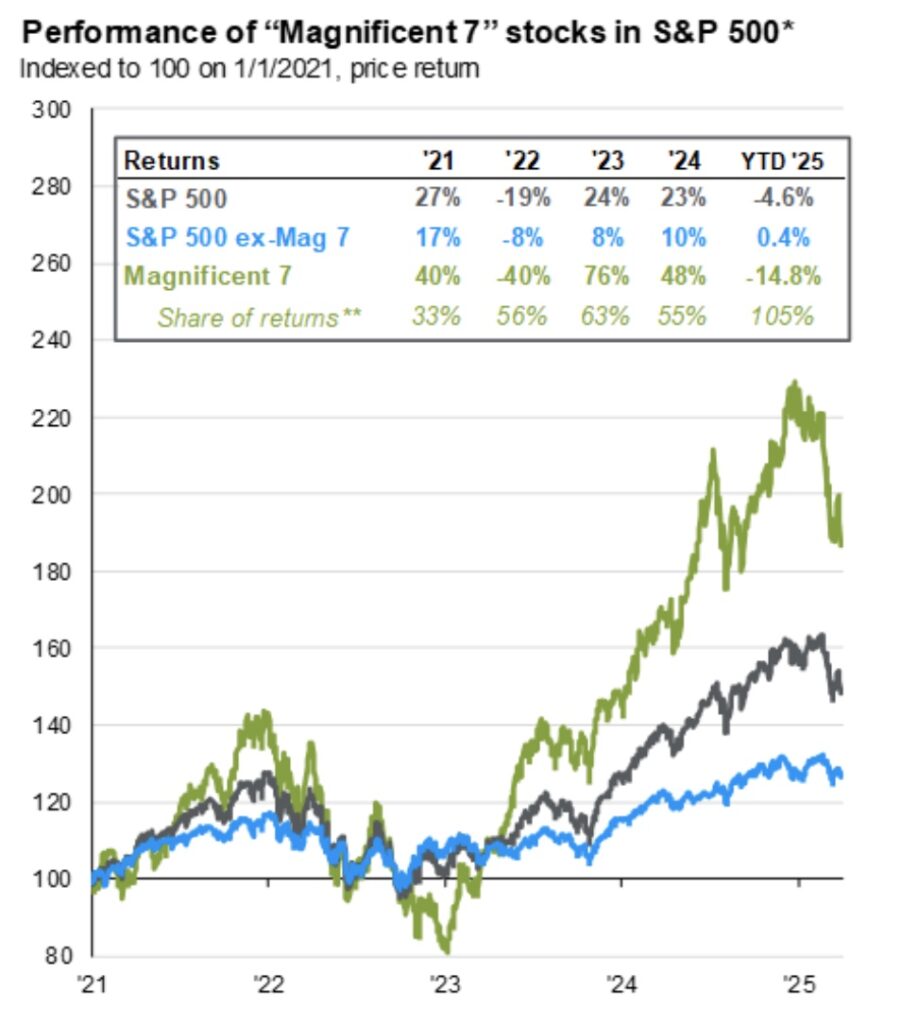
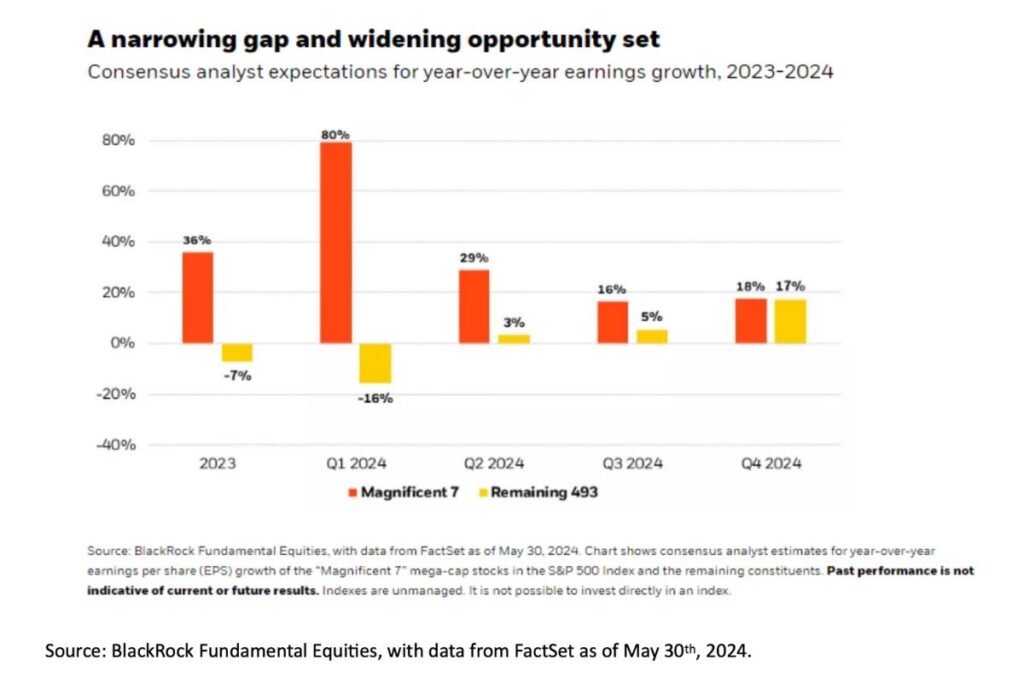
The first quarter of 2025 the S&P 500 Index was down 4.6% following a stellar 2024 that saw the index return over 23%. S&P 500 earnings in the fourth quarter of 2024 grew by 17.1%, with 74% of the companies surprising on the upside and 19% on the downside. Revenue growth for the index was not as strong but still managed to grow 5.1% in the fourth quarter[2]. The Information Technology sector, representing over 30% of the S&P 500, had a drawdown of –11.2%[3] since the beginning of 2025. We have also seen the Magnificent Seven stocks significantly underperforming the other 493 stocks in the S&P 500 in the first quarter, -14.8% vs. 0.4%[4], respectively.

The volatility in this quarter began late January when a Chinese Artificial Intelligence company called “DeepSeek” released its newly developed AI model reporting to have needed a much smaller investment than some of the large U.S hyperscale companies. Adding to the mix is the high valuation that the technology sector had, starting the year with a Price to Earnings ratio of 32.4, and if any news comes out that does not rhyme with perfection it would have and will cause volatility in this sector. On the flip side, the energy sector has enjoyed the best returns since the start of this year, gaining 10%[5], despite the price of oil decreasing in this period. As some of those companies with high valuations face uncertainty, investors are rotating to companies with lower valuations than the S&P 500 such as the ones in the Energy sector, its current price to earnings ratio is 15.7 vs. 20.9[6] of the broader market which would explain the outperformance we have seen thus far in the Energy sector. However, the year is not over yet and there are still many questions and uncertainties the market is waiting on for resolution.

Graph of Magnificent 7 stocks in S&P 500
Figure 2: Source – J.P. Morgan Asset Management, FactSet, Standard & Poor’s. Data as of 03/31/2025.

Fixed Income

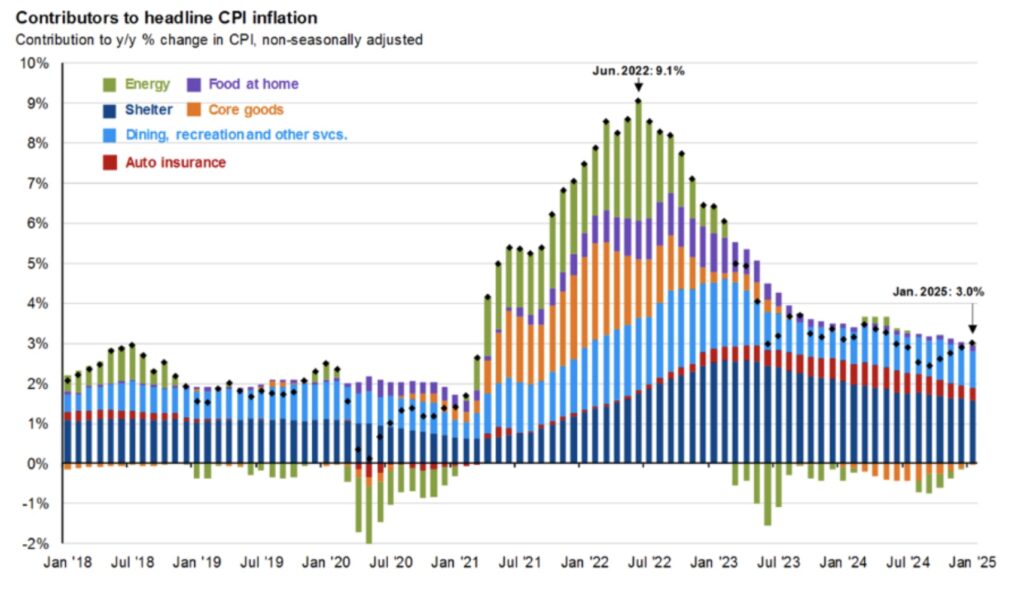
The market is predicting, with a 90% probability, that the Federal Reserve will cut their policy rate by fifty basis points or more by the end of 2025[7]. The Federal Reserve has a dual mandate to maintain price stability and promote maximum employment with the use of monetary policy. As it stands inflation is far from its target and employment, although not at maximum, has shown itself to be stable. Inflation eased a bit over the last twelve months; however, it is proving to be sticky above the Federal Reserve’s 2% target. The Consumer Price Index increased 2.8% year over year in its latest reading at the end of February, within it the shelter index continues to account for most of the level of inflation as seen in figure 3. The unemployment rate has been mostly flat at 4.1% since June of last year[8], however U.S employers announced over 172,000 jobs cuts in February marking the highest monthly total since July 2020[9].

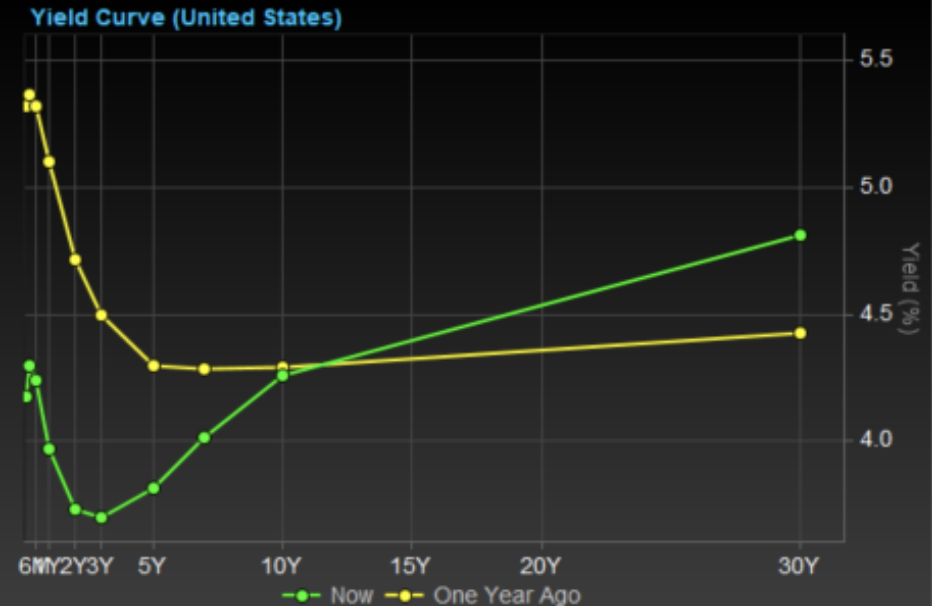
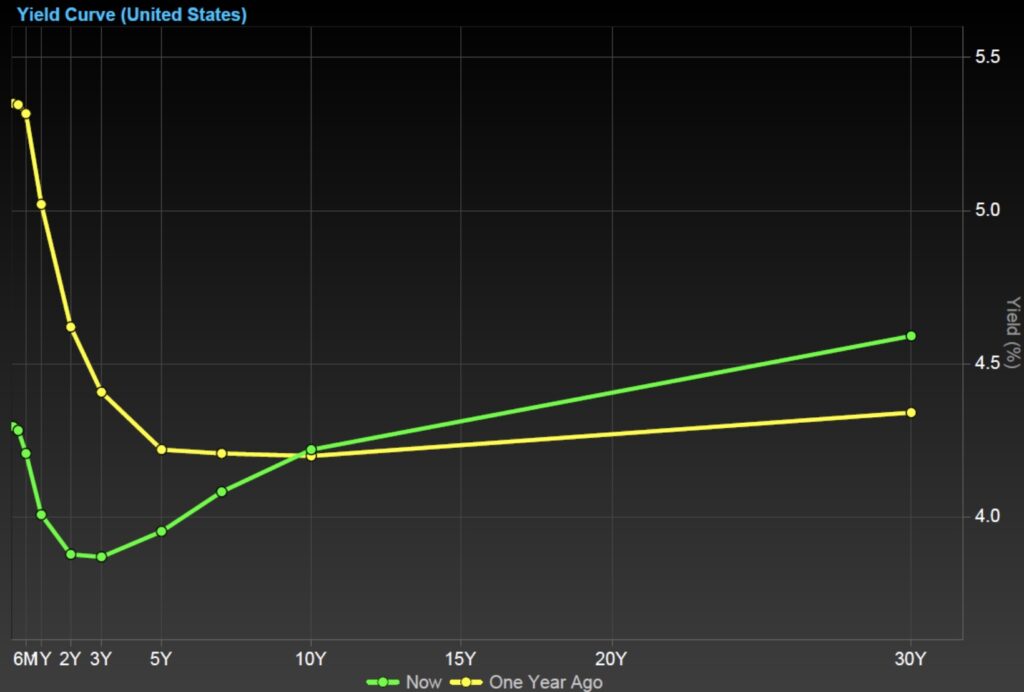
U.S. Treasury yields for mid to long term have decreased since the beginning of the year. The 2-year and 10-year rates both came down nearly forty basis points to 3.9% and 4.2%, respectively[10].

U.S. yield curve comparison chart, current vs. past year.
Figure 3: Sources – FactSet, Tullett Prebon Information.
Bar chart of CPI inflation contributors, 2018-2025.
Figure 4: Source – BLS, FactSet, J.P. Morgan Asset Management: Guide to the Markets. Data are as of March 31, 2025.

Outlook

The financial markets have experienced notable volatility in recent months, driven by a mix of economic data, central bank policies, and global geopolitical events. The equity markets started off the year as the previous two have finished but have reversed direction as they adjust to the issues addressed above and various levels of uncertainty have been introduced. Bond markets continue to adjust to shifting interest rate expectations, with yields fluctuating as investors assess the policy direction of central banks, both domestically and globally. Commodities, such as oil and gold have seen price swings due to supply chain disruptions and safe-haven demand.

Looking ahead, market sentiment will largely be shaped by monetary policy decisions and economic indicators, particularly inflation and employment data. The Federal Reserve and other central banks are expected to carefully balance growth and inflation concerns, with many investors anticipating potential rate cuts later in the year if inflation eases and/or the economy shows weakness. However, uncertainties remain, including geopolitical tensions, evolving trade policies, and risks of economic slowdown both in the U.S. and internationally.

As potential headwinds and further volatility are expected, the financial markets and investors will most likely focus on inflation trends, employment data, and corporate earnings to gauge the market direction, in the short-term and the remainder of the year.

Always vigilant, our commitment to you is to navigate your portfolio through both calm and turbulent times to work towards your long-term goals and objectives.

Footnote 1, 6: FactSet, data as of 04/02/2025.
Footnote 2: London Stock Exchange – S&P 500 Earnings Scorecard, data as of 03/21/2025
Footnote 3, 5: Fidelity, data as of 04/02/2025.
Footnote 4: JP Morgan Asset Management, FactSet, Standard & Poor’s, data as of 03/31/2025.
Footnote 7: CME Group – FedWatch Tool, data as of 04/02/2025.
Footnote 8: US Bureau of Labor Statistics, data as of 03/31/2025.
Footnote 9: Challenger, Gray, & Christmas Inc. 
Footnote 10: CNBC.com, data as of 04/02/2025.

Disclosures

Trust and Portfolio Management services offered by Cypress Bank & Trust are not insured by the FDIC; are not deposits, are not guaranteed; and are subject to investment risks, including possible loss. This does not constitute an offer or solicitation. 

This information should not be considered investment advice. Opinions expressed reflect the judgment of the authors and are current opinions as of the date appearing in this material only. While every effort has been made to verify the information contained herein, we make no representations as to its accuracy and it should not be regarded as a complete analysis of the subjects discussed. Past performance does not predict future results. Content should not be construed as legal or tax advice. Always consult an attorney or tax professional regarding your specific legal or tax situation. All investing involves risk, including the loss of some or all of your investment. 

Any indices and other financial benchmarks shown are provided for illustrative purposes only, are unmanaged, reflect reinvestment of income and dividends and do not reflect the impact of advisory fees. Investors cannot invest directly in an index. Comparisons to indexes have limitations because indexes have volatility and other material characteristics that may differ from a particular fund. 

Certain information contained herein constitutes “forward-looking statements,” which can be identified by the use of forward-looking terminology such as “may,” “will,” “should,” “expect,” “anticipate,” “project,” “estimate,” “intend,” “continue,” or “believe,” or the negatives thereof or other variations thereon or comparable terminology. Due to various risks and uncertainties, actual events, results or actual performance may differ materially from those reflected or contemplated in such forward-looking statements. Nothing contained herein may be relied upon as a guarantee, promise, assurance or a representation as to the future. 

Information obtained from third party sources is believed to be reliable but has not been independently verified and its accuracy or completeness cannot be guaranteed. No representation is made with respect to the accuracy, completeness, or timeliness of this document. 

Specific investments described herein do not represent all investment decisions made by Cypress Bank & Trust. The reader should not assume that investment decisions identified and discussed were or will be profitable. Specific investment advice references provided herein are for illustrative purposes only and are not necessarily representative of investments that will be made in the future. 

Compass on hand with Cypress Bank publication details
The Compass Q4 2024

“History doesn’t repeat itself, but it often rhymes”
-Mark Twain

2024 was another banner year for the stock market. In a year that started with a 7.6 magnitude earthquake hitting Japan and included continued armed conflict in Europe, a collapse of a major bridge in Baltimore, the conviction of Crypto King Sam Bankman-Fried, devastating hurricanes, Iranian missile strikes on Israel along with a small event called a presidential election the markets hit new highs over 55 times in 2024 in spite of all the disruptive events that took place.

As a result of the 23.3% gain in 2024 and the 24.23% return in 2023 the S&P 500 had the first 20% annual returns back-to-back since the late 1990’s [1]. Much of the gain in the S&P 500 can be attributed to a handful of stocks many of which were involved in the Artificial Intelligence segment of the market. 

The outperformance in this sector has resulted in the ten largest stocks in the S&P 500, now representing almost 35% of the entire index capitalization. This amount of concentration in the index has not been seen since the late 1990’s. A corollary of this is that market valuations have now approached or exceeded those levels of the late 1990’s [2].

Admittedly the rage of the late 1990’s was the internet (which has proven to be a game changer in our business and personal lives) and today the thing that garners most of the buzz is Artificial Intelligence.

We at Cypress Bank & Trust are not predicting that we will have a market sell off like we had at the beginning of this century but since our investment approach is grounded in fundamentals and our team has over 100 years of combined experience managing clients’ assets, we are somewhat circumspect regarding current market levels. Rest assured that we remain vigilant in our approach and seek to not only generate quality returns for our clients but also manage the risks of our clients’ portfolios.

Equity

The S&P 500 closed 2024 up 23.3%, marking one of the best years in its history. During the year, the index reached an all-time high a remarkable 57 times, a feat that only happened four other years since 1929 [3]. The combination of interest rate cuts, artificial intelligence, and the incoming Trump administration were some of the main culprits behind this bull market. Market concentrations continued to increase to a high since at least 1996. Compared to the S&P 500’s 2024 return of 23%, the “Magnificent 7” stocks returned over 65% year to date while the Equal Weight S&P 500 Index returned 11%. The same was true for the fourth quarter of 2024, with the “Magnificent 7” returning nearly 20% versus the S&P 500 returning below 4% [4].

As we enter 2025, there are some questions that market participants are still waiting to be answered. Top of the mind is interest rates and inflation uncertainty, a new White House Administration starting on January 20th, and the ongoing geopolitical tensions in Ukraine & Russia, Israel & Iran, and that not so much talked about lately China & Taiwan. However, there are a lot of promising developments shaping up, especially in artificial intelligence and healthcare. 

Fixed Income

The 4th quarter of 2024 in the fixed income markets was marked by declining interest rates in the short end of the yield curve and substantially increasing interest rates in the long end of the yield curve. The 10-year Treasury yield closed Q4 at 4.57%, increasing 83 basis points in the past three months [5]. This measure has a close relationship to mortgage rates, and thus the reason we have seen mortgage rates increasing in the second half of 2024 even though the Federal Reserve (“The Fed”) cut interest rates by a total of 1% in this period.

For 2025, the market is pricing in a range of interest rate cuts in the magnitude of 25 to 75 basis points. However, it remains to be seen how some of the economic data will unfold through the next few months. Inflation has been stubborn in reaching the Fed’s 2% target, unemployment remains at 4.2%, and GDP numbers have been higher than most would have expected.

Outlook

The 4th quarter of 2024 in the fixed income markets was marked by declining interest rates in the short end of the yield curve and substantially increasing interest rates in the long end of the yield curve. The 10-year Treasury yield closed Q4 at 4.57%, increasing 83 basis points in the past three months. This measure has a close relationship to mortgage rates, and thus the reason we have seen mortgage rates increasing in the second half of 2024 even though the Federal Reserve (“The Fed”) cut interest rates by a total of 1% in this period.

For 2025, the market is pricing in a range of interest rate cuts in the magnitude of 25 to 75 basis points. However, it remains to be seen how some of the economic data will unfold through the next few months. Inflation has been stubborn in reaching the Fed’s 2% target, unemployment remains at 4.2%, and GDP numbers have been higher than most would have expected.

1. Investing.com, S&P 500 Year-End Gains Top 20% for Second Year Running, 01/03/2025.
2. FactSet, Standard & Poor’s, J.P. Morgan Asset Management, data as of 11/30/2024.
3. Yahoo Finance, The S&P 500 Just Did Something for Only the 5th Time Ever, 12/08/2024.
4.  FactSet, data as of 01/02/2025
5.  CNBC, data as of 01/02/2025.

Disclosures

Trust and Portfolio Management services offered by Cypress Bank & Trust are not insured by the FDIC; are not deposits, are not guaranteed; and are subject to investment risks, including possible loss. This does not constitute an offer or solicitation.

This information should not be considered investment advice. Opinions expressed reflect the judgment of the authors and are current opinions as of the date appearing in this material only. While every effort has been made to verify the information contained herein, we make no representations as to its accuracy and it should not be regarded as a complete analysis of the subjects discussed. Past performance does not predict future results. Content should not be construed as legal or tax advice. Always consult an attorney or tax professional regarding your specific legal or tax situation. All investing involves risk, including the loss of some or all of your investment.

Any indices and other financial benchmarks shown are provided for illustrative purposes only, are unmanaged, reflect reinvestment of income and dividends and do not reflect the impact of advisory fees. Investors cannot invest directly in an index. Comparisons to indexes have limitations because indexes have volatility and other material characteristics that may differ from a particular fund.

Certain information contained herein constitutes “forward-looking statements,” which can be identified by the use of forward-looking terminology such as “may,” “will,” “should,” “expect,” “anticipate,” “project,” “estimate,” “intend,” “continue,” or “believe,” or the negatives thereof or other variations thereon or comparable terminology. Due to various risks and uncertainties, actual events, results or actual performance may differ materially from those reflected or contemplated in such forward-looking statements. Nothing contained herein may be relied upon as a guarantee, promise, assurance or a representation as to the future.

Information obtained from third party sources is believed to be reliable but has not been independently verified and its accuracy or completeness cannot be guaranteed. No representation is made with respect to the accuracy, completeness, or timeliness of this document.

Specific investments described herein do not represent all investment decisions made by Cypress Bank & Trust. The reader should not assume that investment decisions identified and discussed were or will be profitable. Specific investment advice references provided herein are for illustrative purposes only and are not necessarily representative of investments that will be made in the future.

Hand holding compass, Cypress Bank publication.
The Compass Q3 2024

Is the Federal Reserve on the horns of a dilemma?

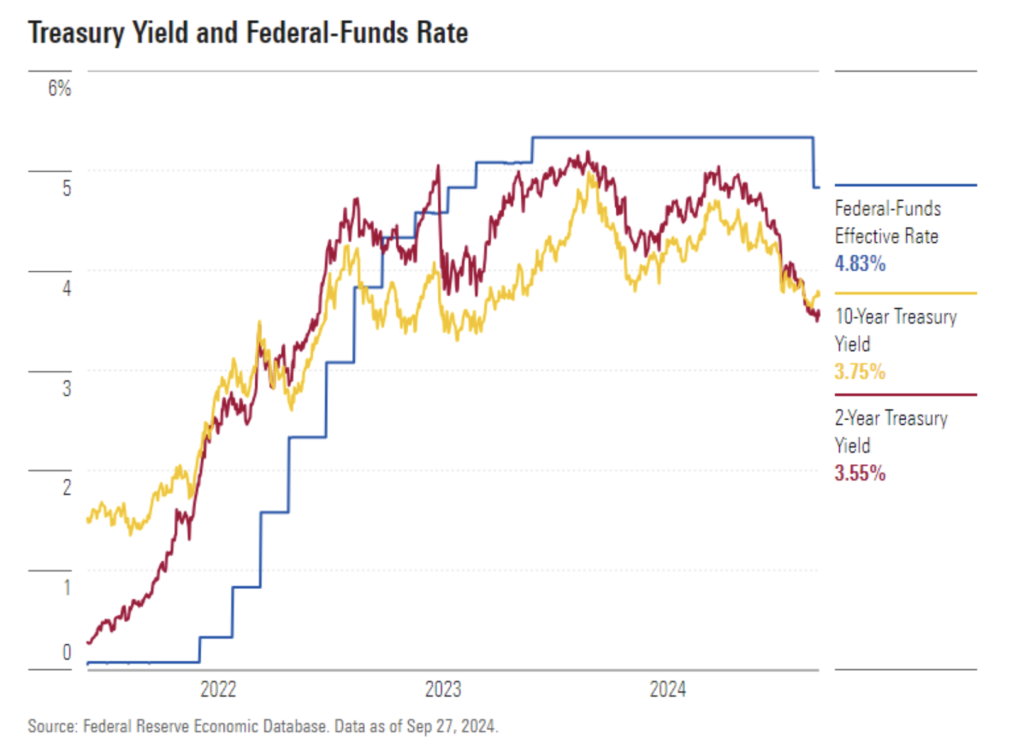
Ever since the Federal Reserve began raising interest rates in March of 2022 Wall Street pundits have been anticipating the eventual easing of interest rates by the Federal Reserve. Over the past twelve months the collective market punditry has speculated that the Federal Reserve will cut rates from zero to seven times this year. Now that the Federal Reserve has begun to cut interest rates at their last meeting in September two questions need to be asked:

1. Are additional rate cuts necessary? 
2. If so, then how many?

Many economic statistics indicate the economy is slowing down, and the Federal Reserve needs to act before more economic damage is incurred. On the other hand, there are just as many economic statistics that indicate that the economy is not in a recession and in fact has been growing, albeit slowly, consistently for the past number of quarters.
As of last quarter, U.S. household wealth rose at almost a 7% annual rate (double the pace of disposable income growth) to a record $184.5 trillion driven primarily from gains in real estate and the stock market. At the same time credit card delinquency rates have doubled off the lows from Q3 2021 and Americans owe a record $1.14 trillion (about $3,500 per person in the US) on their credit cards.

Although unemployment has risen to 4.2% from 3.5% and the number of unemployed people stands at 7.1 million so far this year, there have been almost 1.5 million jobs created. 

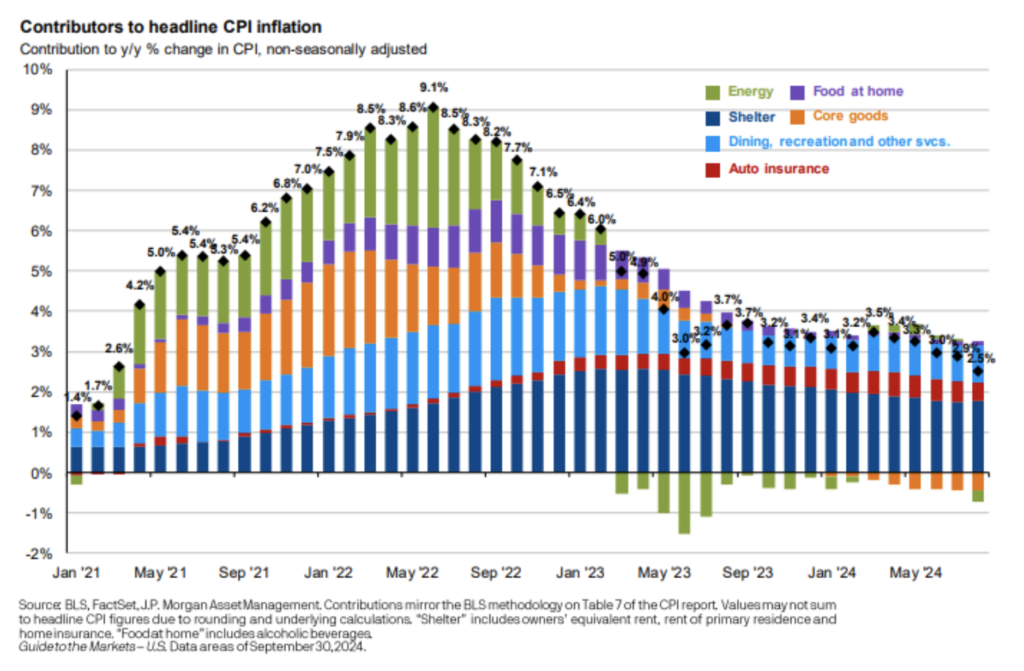
Inflation as measured by the Consumer Price Index has fallen from over 9% annually to 2.5% over the last 12 months. Although the Federal Reserve has a stated 2% annual goal for inflation many members have stated a desire to have additional rate cuts before year end and into 2025.

While some might argue for a significant number of rate cuts there are many who would prefer that the number of rate cuts be kept at a minimum. The impact of these potential cuts will impact not only the stock market but also the amount of interest that investors can earn along with the price of real estate and other assets in addition to the overall economy.

As the Federal Reserve wrestles with this dilemma, we at Cypress Bank & Trust are diligently evaluating the various market forces that can impact our clients’ portfolios and aiming to determine how to best position them so that we can take advantage of the potential opportunities that the markets present. There is no single investment or portfolio that is right for every investor, that is why we seek to tailor our solutions for each client’s specific needs and goals.

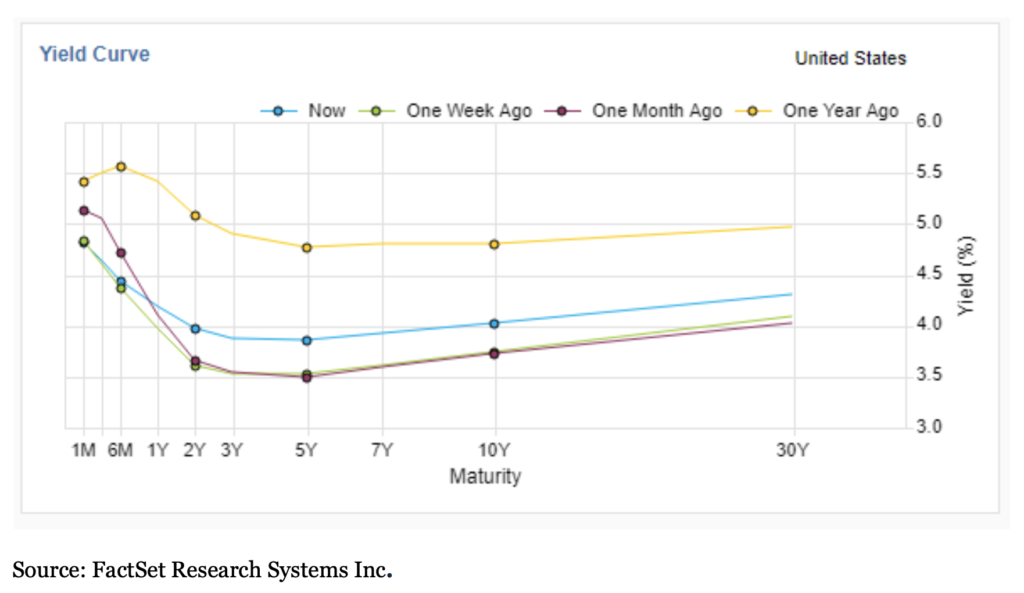
US yield curve graph with maturity and yield values.

Equities

The third quarter roller coaster has finally come to a halt. Although the mood of investors ended the quarter on a positive note, let’s not forget how we got here. The stock market, as measured by the S&P 500 Index, finished Q3 with a 5.6% return for the quarter and a 22% return year to date. However, in early August we witnessed the S&P 500 have its largest single day drop of 3% in nearly two years because of the Japanese Yen carry trade unwind. Some market participants were even calling for an emergency interest rate cut from the Federal Reserve, an act that we have seen happen twice in the past 20 years; during the Great Financial Crisis in 2008 and the Covid-19 pandemic in March of 2020. The markets did calm down and returned to their positive trajectory once economic data releases, like the Consumer Price Index (CPI) and the Personal Consumption Expenditures Index (PCE), showcased the inflation rate moving towards its 2% target. On their September 18th Federal Open Market Committee meeting, the Federal Reserve did begin its much-anticipated interest rate cutting cycle with a large 50 basis point cut, a move that saw the S&P 500 rally nearly 3% in these last two weeks of the quarter. Market gyrations can be overwhelming if looked at within a short time frame and that’s why here at Cypress Bank & Trust we believe in staying invested for the long term as the best chance of achieving your return goals.

Market rotation was another big theme during Q3, as some of the underperforming sectors and pockets of the market exhibited overperformance during this quarter. The equal weighted S&P 500 had nearly double the return of the market weighted index at 10.4% for Q3 as measured by the Invesco S&P 500 Equal Weight ETF (RSP). We also saw the semiconductor industry have a return of -5% for the quarter, measured by the VanEck Semiconductor ETF (SMH), against a return of over 10% for the Russell 2000 Index (Mid and Small caps). Lastly, the top three performing sectors in Q3 were Utilities, Real Estate, and Industrials returning 19.4%, 15.5%, and 11.1%, respectively, while the bottom 3 sectors were Technology, Energy, and Communication Services with returns of -1.25%, -0.95%, and 1.82%, respectively.

Graph of CPI inflation contributors by category, 2021-2024.

Fixed Income

The Treasury yield curve has been inverted (2-year yields being higher than the 10-year yields) for the longest stretch of time on record since July of 2022. An inverted yield curve has historically been a sign that a recession is looming, however; one has not yet arrived. In August of this year, the yield curve finally normalized as expectations of an interest rate cut increased after a series of good inflation data and weakening labor markets reports were released.

The Federal Reserve did indeed cut their benchmark rate by 50 basis points, to the surprise of many, to take their current target range from 4.75% to 5%. There are expectations that the Federal Reserve will continue to move on with its cutting rate cycle through the rest of 2024 and into the first few meetings of 2025.

Congruent to the Equity markets, gains in the broad Fixed Income markets continued to pile on during the third quarter. Yields on Treasury notes for all durations fell throughout the third quarter. As yields fell bonds had some price appreciation, the Bloomberg US Aggregate Index (the most used fixed income index in the US) gained 5.8% for Q3, and over the past 12 months it has gained 11.6%.

Graph of treasury yields, federal funds rate trends.

Outlook

As we look ahead to the next quarter, the market outlook reflects a mix of cautious optimism and underlying challenges. Economic indicators suggest moderate growth, driven by consumer spending and a resilient labor market. However, inflationary pressures continue to influence monetary policy, with potential for interest rate adjustments that could impact borrowing costs and consumer confidence. Investors are closely watching central bank signals, which will play a crucial role in shaping market sentiment.

Additionally, geopolitical tensions and supply chain disruptions remain significant factors that could introduce volatility. The upcoming election may also introduce uncertainty into the markets. We will stay informed and adaptable, considering both opportunities and risks as we approach this final quarter of 2024, and the calendar turns to 2025.

Always vigilant, our commitment to you is to navigate your portfolio through both calm and turbulent times to work towards your long-term goals and objectives.

Disclosures

Trust and Portfolio Management services offered by Cypress Bank & Trust are not insured by the FDIC; are not deposits, are not guaranteed; and are subject to investment risks, including possible loss. This does not constitute an offer or solicitation.

This information should not be considered investment advice. Opinions expressed reflect the judgment of the authors and are current opinions as of the date appearing in this material only. While every effort has been made to verify the information contained herein, we make no representations as to its accuracy and it should not be regarded as a complete analysis of the subjects discussed. Past performance does not predict future results. Content should not be construed as legal or tax advice. Always consult an attorney or tax professional regarding your specific legal or tax situation. All investing involves risk, including the loss of some or all of your investment.

Any indices and other financial benchmarks shown are provided for illustrative purposes only, are unmanaged, reflect reinvestment of income and dividends and do not reflect the impact of advisory fees. Investors cannot invest directly in an index. Comparisons to indexes have limitations because indexes have volatility and other material characteristics that may differ from a particular fund.

Certain information contained herein constitutes “forward-looking statements,” which can be identified by the use of forward-looking terminology such as “may,” “will,” “should,” “expect,” “anticipate,” “project,” “estimate,” “intend,” “continue,” or “believe,” or the negatives thereof or other variations thereon or comparable terminology. Due to various risks and uncertainties, actual events, results or actual performance may differ materially from those reflected or contemplated in such forward-looking statements. Nothing contained herein may be relied upon as a guarantee, promise, assurance or a representation as to the future.

Information obtained from third party sources is believed to be reliable but has not been independently verified and its accuracy or completeness cannot be guaranteed. No representation is made with respect to the accuracy, completeness, or timeliness of this document.

Specific investments described herein do not represent all investment decisions made by Cypress Bank & Trust. The reader should not assume that investment decisions identified and discussed were or will be profitable. Specific investment advice references provided herein are for illustrative purposes only and are not necessarily representative of investments that will be made in the future.

The Compass Q2 2024

“It was the best of times, it was the worst of times, it was the age of wisdom, it was the age of foolishness, it was the epoch of belief, it was the epoch of incredulity, it was the season of light, it was the season of darkness, it was the spring of hope, it was the winter of despair.”

― Charles Dickens, A Tale of Two Cities

While Dickens was contrasting the lives of three families in London and Paris during the French Revolution, we think he could easily have been describing the stock market in 2024. For investors who owned a small select group of stocks (specifically Nvidia, Taiwan Semiconductor, Eli Lilly, Broadcom & Qualcomm) your return so far in 2024 is in excess of 70%. If on the other hand you owned the Dow Jones Industrial Average your return year to date is 5%, which pales in comparison.

For the year, the S&P 500 is up 15% and it is commonly known that Nvidia, Microsoft, Meta, Alphabet, Amazon, and Apple account for over 60% of the S&P 500’s year to date gain. What is less well known is that the average stock is priced about where it was at the start of 2022. 

As a result of their epic move, Nvidia, Microsoft and Apple now account for over 20% of the entire S&P 500 market capitalization. Historically this type of market concentration has proven to be an inflection point in the market. Only time will tell if this time will be different or not but we at Cypress Bank & Trust are not sitting on our hands. We expend a significant amount of time and energy not only researching the positions to add to our clients’ portfolios but also quite a bit of time evaluating the existing holdings in our clients’ portfolios.

In this way we can properly weigh potential risks and return opportunities that the markets, asset classes and specific securities offer our clients. The outcome is a customized portfolio that is bespoke for each client so we aim to achieve the specific goals and characteristics tailored to each client.

As such we are better able to position our clients’ portfolios over a wide ranging variety of market outcomes because our experience has taught us that no matter how optimistic or pessimistic the market is about future events just as we saw in A Tale of Two Cities, things are not always what they seem and it is our commitment to our clients to endeavor to discern the difference.

Equities

The U.S. stock market has continued its upward trajectory during the second quarter. The S&P 500 index closed the quarter at an all-time high for the second quarter in a row. The S&P 500 was up 4% in the second quarter, taking the year-to-date return to over 15%. The Nasdaq Composite, which has a high exposure to Technology, had a return of 8% for the quarter while the Dow Jones Industrial Average retreated nearly 2%.

In Q1 of 2024, the S&P 500 saw their earnings grow 5.9% year over year. Identical to the Q4 of 2023, the sectors with double digit growth in Q1 of 2024 were Communication Services, Consumer Discretionary, Utilities, and Technology. However, Materials, Healthcare, and Energy sectors saw negative earnings growth. The variance between the top and bottom performing sector was 59%. As for revenues, the spread was much narrower at 16%. Of the 11 sectors, 8 saw positive revenue growth ranging from 3% to 8%.

In this first half of 2024, we have seen the concentration further increase in the S&P 500. The Magnificent 7 (composed of Apple, Microsoft, Alphabet, Amazon, Nvidia, Meta Platforms, and Tesla) had a 33% return year to date, while the S&P 500 ex-Magnificent 7 had returns of a mere 5%. The Invesco S&P 500 Equal Weight ETF (Exchange Traded Funds) also returned 5% for the first half, while retreating 3% in the most recent Q2.

There is optimism the Federal Reserve will finally start cutting interest rates this year as early as September. To offset this optimism, geopolitical tensions are still high along with the looming presidential elections in the US and globally, in which many market impacting issues are up for debate. 

Fixed Income

Treasury yields displayed heightened volatility in the beginning of the second quarter, as inflation figures for the beginning of the year were hotter than expected. The Federal Reserve (the Fed) held two meetings in this past quarter where it decided to hold interest rates steady. However, during their May meeting, the Fed announced a decrease in the speed of its balance sheet runoff by shrinking the current cap of $60 billion to $25 billion per month of US Treasury securities it lets mature and not be replaced. The Fed’s balance sheet runoff is often referred to as quantitative tightening (QT), and as the name implies it is meant to decrease excessive liquidity in the economy. The change in the runoff cap by the Fed is aimed at decreasing the pace of QT and keeping longer term interest rates more stable as the Fed only has control over short-term rates. In their June meeting, the Federal Reserve released the “dot plots” (the expected path for rates) where it targeted one cut by the end of 2024, a shift from their previous expectations of three cuts.

The unemployment rate increased during the second quarter, although it has only done so incrementally from 3.9% to 4% in the last reading. In terms of inflation, we have seen it come down drastically from 2022 where it was as high as 9%, but it has been stuck around 3% since the summer of 2023. The interest rate path forward will depend on several factors, the two most important being inflation and employment levels.

Outlook

Predictions of a recession have come in waves through the last 3 years, and yet here we still stand. While the scare of a recession is still afloat, it has reasonably retreated in these past six months. On one side of the coin, inflation figures have substantially improved, unemployment remains below the historical average, and the stock market is continually topping its all-time highs. The other side of the coin is a bit grimmer as geopolitical risk remains high, inflation is proving to be sticky at around 3% which is above the Fed’s 2% target, and the stock market is breaking records in concentration risk and high valuations multiples. At last, we still have an election in November which has implications in taxes, government spending, and global trade. So, where does our economy go from here? Here at Cypress Bank & Trust, we maintain investors should stay focused on the long-term and maintain adequate diversification to help them navigate these uncertainties.

Always vigilant, our commitment to you is to navigate your portfolio through both calm and turbulent times to work towards your long-term goals and objectives.

We hope you and your family have a healthy and fulfilling summer!!!

Disclosures

Trust and Portfolio Management services offered by Cypress Bank & Trust are not insured by the FDIC; are not deposits, are not guaranteed; and are subject to investment risks, including possible loss. This does not constitute an offer or solicitation.

This information should not be considered investment advice. Opinions expressed reflect the judgment of the authors and are current opinions as of the date appearing in this material only. While every effort has been made to verify the information contained herein, we make no representations as to its accuracy and it should not be regarded as a complete analysis of the subjects discussed. Past performance does not predict future results. Content should not be construed as legal or tax advice. Always consult an attorney or tax professional regarding your specific legal or tax situation. All investing involves risk, including the loss of some or all of your investment.

Any indices and other financial benchmarks shown are provided for illustrative purposes only, are unmanaged, reflect reinvestment of income and dividends and do not reflect the impact of advisory fees. Investors cannot invest directly in an index. Comparisons to indexes have limitations because indexes have volatility and other material characteristics that may differ from a particular fund.

Certain information contained herein constitutes “forward-looking statements,” which can be identified by the use of forward-looking terminology such as “may,” “will,” “should,” “expect,” “anticipate,” “project,” “estimate,” “intend,” “continue,” or “believe,” or the negatives thereof or other variations thereon or comparable terminology. Due to various risks and uncertainties, actual events, results or actual performance may differ materially from those reflected or contemplated in such forward-looking statements. Nothing contained herein may be relied upon as a guarantee, promise, assurance or a representation as to the future.

Information obtained from third party sources is believed to be reliable but has not been independently verified and its accuracy or completeness cannot be guaranteed. No representation is made with respect to the accuracy, completeness, or timeliness of this document.

Specific investments described herein do not represent all investment decisions made by Cypress Bank & Trust. The reader should not assume that investment decisions identified and discussed were or will be profitable. Specific investment advice references provided herein are for illustrative purposes only and are not necessarily representative of investments that will be made in the future.


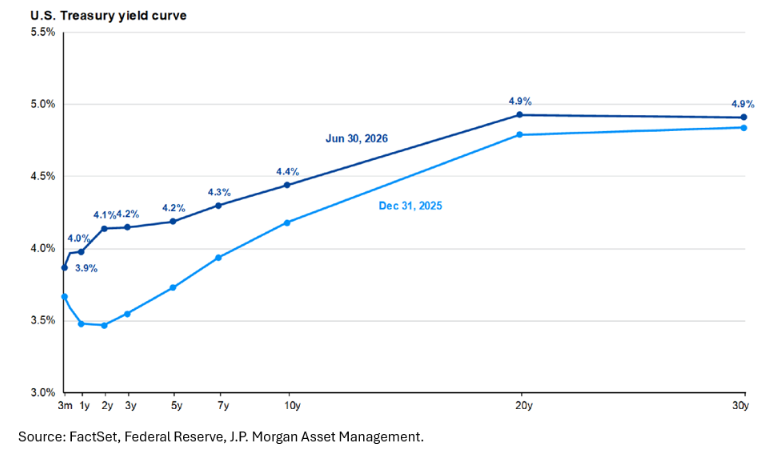
Compass in hand, April 2024 publication cover.
The Compass Q1 2024

“I skate to where the puck is going to be, not where it has been.”
-Wayne Gretzky aka “the Great One”
Nine-time winner of the Hart Trophy (NHL Most Valuable Player)

INVESTMENT UPDATE

This year’s market advance (saying nothing of the advance since the end of October 2023) has been breathtaking to say the least. While 2023 was dominated by the Magnificent Seven (Apple, Amazon, Alphabet, Meta, Microsoft, Nvidia, and Tesla) so far in 2024 the market has broadened out to include many other stocks and sectors. In fact, the two leading sectors so far in 2024 are Energy and Communication Services.

For the 1st quarter of 2024 the S&P 500 was up 10%, which would be annualized out to almost 50% if the market continues at this pace. Although S&P 500 earnings are expected to grow by approximately 10% in 2024 there have not been any significant upward revisions to these estimates since the end of the 3rd quarter of 2023 along with the fact that the 10-year Treasury Note yield has increased from 3.90% at the end of 2023 to 4.20% currently. The significance of these points is that almost the entire move in the equity market can be explained by the multiple expansion of the Price to Earnings ratio.

Said a different way, investors are paying more today for a $1 worth of future earnings than they were 5 months ago.
So, what are investors to do? While the easy approach would be to continue to invest in the “hot” sectors of the market, we at Cypress Capital Group subscribe to a more rigid investment process than just chasing the most recent fad. Like how Wayne Gretzky approached hockey, we believe in using our quantitative investment approach where we can identify tomorrow’s opportunities today. In this way, we strive to minimize the risk of getting caught up in the emotional throes of the market and make sound investment choices for our clients’ portfolios. Admittedly, this approach requires a certain degree of patience, which is often said to be the rarest commodity on Wall Street, but our experience has taught us that in order to responsibly manage and grow wealth an investor needs to be patient.

THE MARKET UPDATE

Equities

The equity markets started off at a positive pace to begin the year. The S&P 500 ended the quarter at an all-time high along with posting the best first quarter in some 5 years. The S&P 500 was up just over 10% for the quarter, while the Dow Jones Industrial Average and Nasdaq also participated, up 5.6% and 9.1%, respectively. Much like 2023 ended, the market’s gains were pushed by the excitement around artificial intelligence (“AI”) and the demand for stocks that had exposure to that industry. While those stocks associated with AI led the markets early on, there was some broadening out towards the end of the quarter. The Invesco S&P 500 Equal Weighted index participated also, outpacing the major indices for the month and up greater than 7% in the quarter.

As for earnings, the S&P 500 delivered 10.1% growth in 4Q23. This was driven by double digit growth by Communication Services, Consumer Discretionary, Utilities, and Technology. These growth numbers were dragged down by Health Care, Materials, and Energy. There was a significant spread between the top and bottom section of some 74%. Each reported negative earnings for the quarter. Revenues by comparison were up 3.7% for the most recent quarter. These numbers did not have the variance that

earnings had. There was only an 18% variance. Of the 11 major sectors, only 3 had negative results: Materials, Utilities, and Energy. The remaining sectors are reported at between 2.9% (Consumer Staples) and 7.9% (Technology). Source: LSEG S&P 500 Earnings Scorecard as of 3/28/24

Where do we go from here… The markets have all been positive not only since the beginning of the year, but also looking back to the lows posted in October. Prices have moved higher and while some stocks have gotten cheaper on a valuation basis, the major indices have not. Going forward, what are investors going to do? Will they continue to stay invested in those names that have outperformed, and do they continue to deliver based on expectations? Or is there broadening of the market participation that is sustainable? For either decision, what are investors willing to pay based upon interest rates and their direction? These seem like the same questions we have been asking for the last year plus. Will we get any answers or continue to climb those walls of worry?

Fixed Income

The fixed income markets continue to be volatile, but at the intermediate to long end of the curve. While the Fed has hinted at lowering rates, the evidence of when and how much continues to be the major discussion. Late in 2023 the Fed issued their “dot plots” (the expected path for rates) and targeted some 3 cuts in 2024. There was a major disagreement as the market had forecasted 6 – 7 cuts. Three months into 2024, both seem to have been way off. The Fed has an expectation of 0-2 cuts now, while the markets are betting on 1-3 cuts. This uncertainty has added to confusion and volatility in all markets. Numbers across the economy have been mixed while inflation remains sticky around the 3% level and job growth remains persistent (unemployment rate remains below 4%). The short end of the curve will not begin to move until the Fed starts to cut but the benchmark 10-year US Treasury continues to move based on those expectations for future cuts and more importantly the reasons for the cuts or the impact on the economy. The 10-year US Treasury closed the quarter with a 4.26% yield. In the last couple of days, it has even pushed slightly higher, putting it at levels we have not seen since late 2023. Where we go from here will be based on both the Federal Reserve and the economy, and their impact on each other.

OUTLOOK

If the year ended now most investors would be happy with a double-digit return, and to get that in only 3 months is even more impressive. That is on top of the gains investors got in 2023. But most investors, while concerned with the short run, own equities for longer-term appreciation. That is what has investors on uneasy ground. The yield curve has given investors an alternative to stocks with Treasuries maturing within the next 12 months still yielding over 5% with much less inherent risk. Going forward, we all ask the same question – is the risk worth the reward? This is also a question the Federal Reserve seems to be asking. Not what is the Fed’s next move in interest rates, but when will their first cut take place? One of the questions we continue to ask is – what will be the Fed’s rationale for the looming rate cut? With a stronger than expected economy and an inflation rate that appears to be sticky around the 3% level, currently we are having a tough time producing a reason for the first and subsequent rate cuts. Earnings and expectations around those reports will help drive investor sentiment going forward.

Trust and Portfolio Management services offered by Cypress Bank & Trust are not insured by the FDIC; are not deposits, are not guaranteed; and are subject to investment risks, including possible loss. This does not constitute an offer or solicitation.

This information should not be considered investment advice. Opinions expressed reflect the judgment of the authors and are current opinions as of the date appearing in this material only. While every effort has been made to verify the information contained herein, we make no representations as to its accuracy and it should not be regarded as a complete analysis of the subjects discussed. Past performance does not predict future results. Content should not be construed as legal or tax advice. Always consult an attorney or tax professional regarding your specific legal or tax situation. All investing involves risk, including the loss of some or all of your investment.

Any indices and other financial benchmarks shown are provided for illustrative purposes only, are unmanaged, reflect reinvestment of income and dividends and do not reflect the impact of advisory fees. Investors cannot invest directly in an index. Comparisons to indexes have limitations because indexes have volatility and other material characteristics that may differ from a particular fund.

Certain information contained herein constitutes “forward-looking statements,” which can be identified by the use of forward-looking terminology such as “may,” “will,” “should,” “expect,” “anticipate,” “project,” “estimate,” “intend,” “continue,” or “believe,” or the negatives thereof or other variations thereon or comparable terminology. Due to various risks and uncertainties, actual events, results or actual performance may differ materially from those reflected or contemplated in such forward-looking statements. Nothing contained herein may be relied upon as a guarantee, promise, assurance or a representation as to the future.

Information obtained from third party sources is believed to be reliable but has not been independently verified and its accuracy or completeness cannot be guaranteed. No representation is made with respect to the accuracy, completeness, or timeliness of this document.

Specific investments described herein do not represent all investment decisions made by Cypress Bank & Trust. The reader should not assume that investment decisions identified and discussed were or will be profitable. Specific investment advice references provided herein are for illustrative purposes only and are not necessarily representative of investments that will be made in the future.
Newsletter

Stay connected and discover how Cypress Bank & Trust can be your partner in achieving your financial goals.

KEEP IN TOUCH

Sign Up
Scroll to Top
Florida Trend 2026 Best Companies Winner badge

Named Florida's #1 Best Company to Work For